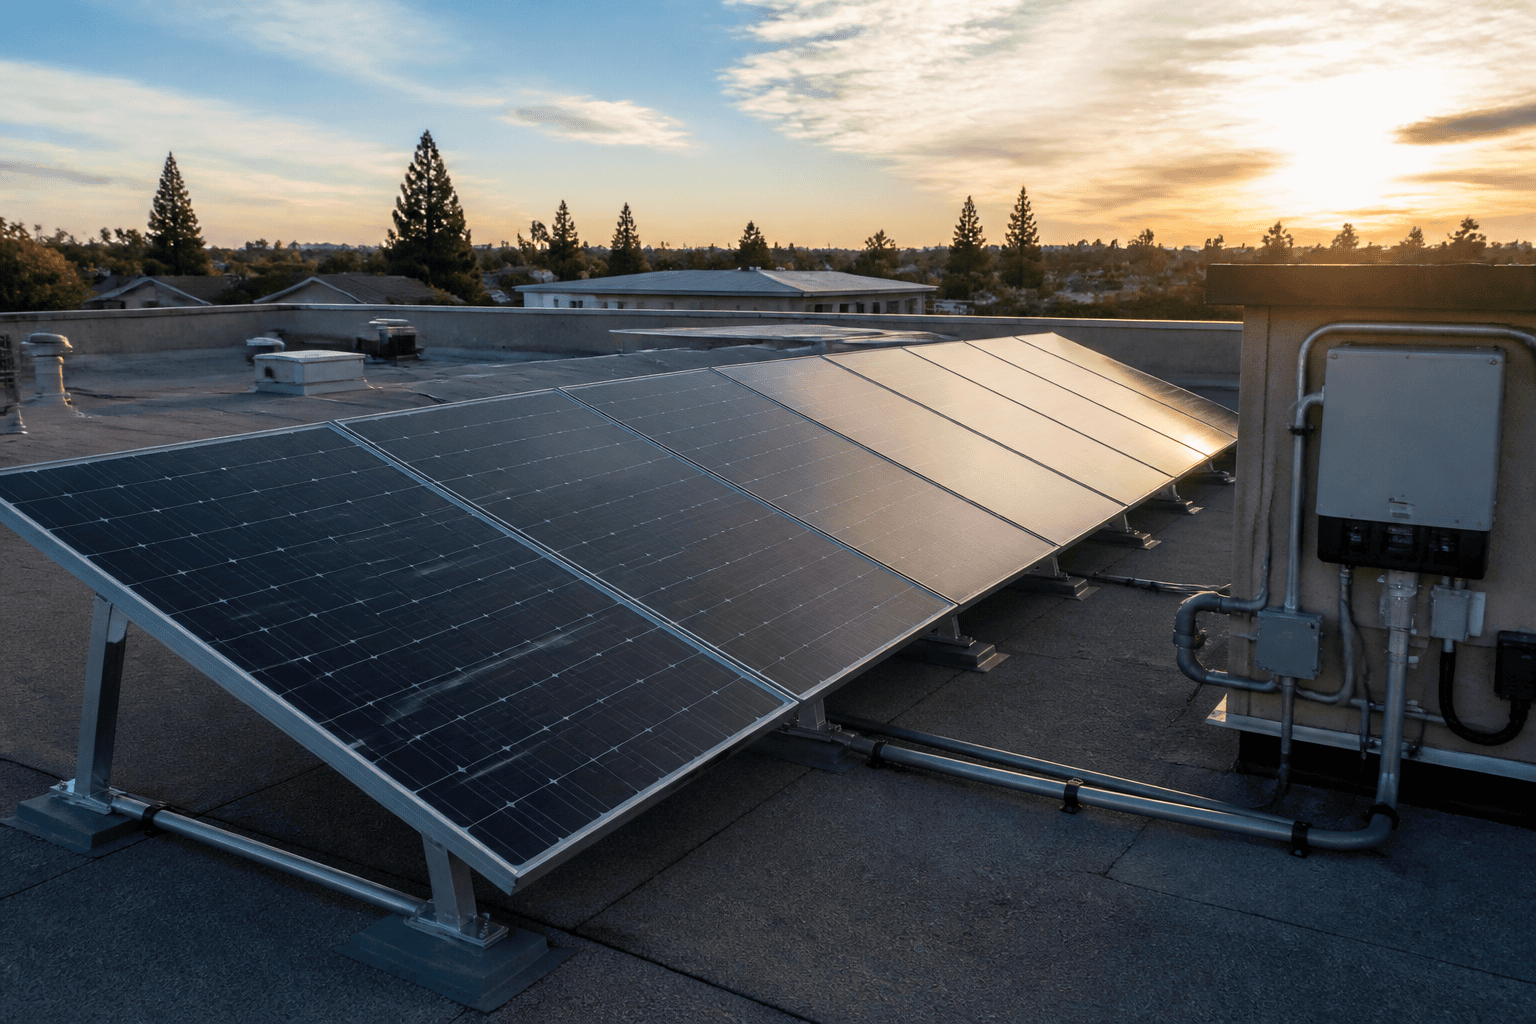
A roof array on a Henderson tract home and a ground-mount on a Phoenix warehouse roof can share one electrician. They do not share one insurance file. Solar contractor insurance is the program for crews who install photovoltaic systems on someone else’s property. It sits beside electrical contractor insurance, which is the full trade stack. The solar invoice is this file. It is not coverage for a homeowner who already has panels, and it is not an EV charger install. We wrote this page for the installer who owns the array invoice. We are an independent agency in Henderson, licensed in Nevada, California, Arizona, and Utah. For the generic contractor stack that applies to every trade, see contractor insurance explained.
Who Needs Solar Contractor Insurance?
This page is for licensed crews who install photovoltaic modules, racking, inverters, and related gear on someone else’s roof or lot. Residential rooftop work belongs here. So does a commercial roof mount, a carport canopy, and many ground-mount packages. The invoice has to name solar or PV. A service-panel upgrade with no array on the ticket is ordinary electrical work. See the electrical contractor guide for that book. See EV charging contractor insurance when the invoice is a wallbox or DC fast pedestal, not modules. See general contractor insurance when you run the whole site and hire the other trades.
Homeowners who already have panels ask a different question. That conversation lives on our home insurance pools, trampolines, and solar guide and the matching state pages. We stay on the installer file here.
What Coverage Does a Solar Installer Need?
Most installer operations run on five core policies. General liability sits at the base. It responds when your work injures a third party or damages their property. Think of a homeowner who slips on a temporary roof edge. Think of a drill that hits a post-tension slab and a vehicle that takes a scuff from a staging cart. Workers compensation covers an installer who is burned, shocked, or hurt from a fall or a lift. Commercial auto covers the trucks that haul modules and racking between sites. Inland marine, often sold as a tools and equipment floater, covers meters, torque tools, and spare modules wherever they travel. An installation floater covers the array itself from the shop to acceptance. A business owners policy can bundle general liability with property coverage for a shop.
Two more deserve a look as you grow. A commercial umbrella stacks extra limits above general liability and auto. Builders and property managers now ask for extra limit before they let a crew on a roof. Professional liability responds to claims about the work itself, such as a layout or load calculation that missed the structure. General liability treats those as professional or workmanship disputes and steps aside. Groups such as the U.S. Department of Energy’s Solar Energy Technologies Office photovoltaics pages publish the technology notes underwriters actually read once a book is mostly PV.
Which Policy Pays Which Solar Claim?
Coverage questions get easier when you map real claims to the policy that responds. The table below covers the losses we see most often in this trade.
| The claim | The policy that responds |
|---|---|
| Homeowner or neighbor slips on temporary roof edge during an install | General liability |
| Installer is burned, shocked, or hurt from a fall, lift, or hot roof | Workers compensation |
| Meter, torque wrench, or spare modules stolen from the truck overnight | Inland marine tools and equipment |
| Modules or inverter damaged in transit before the owner accepts the job | Installation floater |
| Truck hits a parked car between rooftops | Commercial auto |
| A fire or water intrusion traces to the array months after you leave | Completed operations on the general liability policy, if the damage is to other property |
| The modules you just set fail and the owner wants a redo | Often excluded as your work or property in your care |
| Owner says the layout or load calculation missed the structure | Professional liability, or your own pocket |
| Spare modules burn in the shop after hours | Commercial property on the shop, not the installer GL |
Two rows in that table carry an asterisk in real life. Damage to the modules you are setting often sits outside general liability. Fire or smoke that ruins the attic or the next bay is a different claim. We cover both below.
Panels on a House Are a Homeowners Question
If you already own the house and the panels, the insurance conversation is homeowners, not installer general liability. Tell your agent the panels are there. Ask how the dwelling limit treats the array and how a claim splits between the roof and the modules. That is the HO-3 side of the ledger. Start on pools, trampolines, and solar, then the matching state pages for Nevada, California, Arizona, and Utah. This page stays with the crew that hung the array for someone else.
Electrician vs Solar Contractor
Many solar invoices share an electrical family on the license table. That does not make every electrical file a solar file. Electrical contractor insurance is the full trade stack: service, lighting, panels, and commercial wiring. Solar contractor insurance is the installer GL file for photovoltaic work, including racking, roof penetrations, and completed operations on the array. EV charger work is a third invoice. Bid solar on a lighting-and-receptacle class and the rating may not follow the modules. The wrong class is a rating problem. It is not a magic void. State electrical pages: Nevada, California, Arizona, and Utah.
Equipment Breakdown Is a Separate Conversation
Sudden mechanical or electrical breakdown of covered equipment is often a different form than installer general liability. Inverters, transformers, and related gear can sit in that gap once the owner accepts the system. Our equipment breakdown coverage guide explains the homeowners and business side of that form. We mention it here so you do not expect the installer GL to rebuild a failed inverter years later. It is an H2, not a second solar pillar.
Commercial Property for the Shop
The shop is a property story. Spare modules, inverters, racking, and a small warehouse of waiting gear do not ride on general liability. A business owners policy or a standalone commercial property form covers the premises, the stock, and the tools that stay put. Heat in a closed Henderson warehouse and a winter leak in a Utah County bay are both shop claims.
General liability will not rebuild the storage cage after a fire. Inland marine will not replace inventory that never left the building. Put the shop on the right form. Our commercial property insurance page is the service file for that building. Name the shop on the application so the inventory is actually insured.
Commercial Auto for the Installer
The truck that hauls modules is not the homeowner’s car in the driveway. Installer commercial auto covers the vans and flatbeds running between shops and rooftops. It also has to see hired and non-owned use when an employee grabs parts in a personal vehicle. A personal auto policy is a weak home for that trip.
The truck policy lives on our business auto insurance page. Henderson crews can start on Henderson commercial auto insurance. Keep the truck and the client home on separate applications so the class stays honest.
How Do Licensing Rules Differ in Nevada, California, Arizona, and Utah?
Each of the four states we serve puts photovoltaic installation on a solar or electrical family, not on a blank “green energy” product name. Some split module work from NEC wiring. The table is the short version.
| State | Installer card | Watch the split | Bond or insurance rule |
|---|---|---|---|
| Nevada | C-2g Photovoltaics; full C-2 when work goes past the service panel | C-2g covers cells, batteries, and inverters converting solar to electricity; not wiring beyond the service panel; not utility-scale production for sale | Bond $1,000 to $500,000; license carries a monetary limit; workers comp for employees; board does not require general liability |
| California | C-46 Solar; C-10 Electrical also names PV | C-46 is thermal and PV; CSLB adopted an 80 kWh incidental battery limit for C-46 in 2024; a court injunction halted enforcement and CSLB has agreed to revise it, so check the current CSLB position before bidding storage; C-10 is still the broader electrical card | $25,000 contractor bond; sole proprietor specialty cards often have no general liability mandate; LLC needs at least $1 million aggregate (five or fewer people on the license); workers comp once you have help; universal workers comp January 1, 2028 |
| Arizona | R-11, C-11, or CR-11 Electrical for PV electrical scope; solar contractor qualification also required by statute | C-78 is solar plumbing, liquid systems only, not a PV array; “including solar” plumbing and HVAC cards are not the PV electrical file | Bonds scale with class and volume; license at $1,000 or any permit; registrar does not require general liability; workers comp at one employee |
| Utah | S202 Solar Photovoltaic; E200 General Electrical includes S202 as a subclass in the Division’s classification rule | S202 covers modules and related components; it excludes NEC wiring and may hire E200 or E201 for that work | Licensed classes: a current general liability floor around $1 million per occurrence and $2 million aggregate; workers comp or a Labor Commission waiver |
Watch the labels. A Nevada C-2g card is not a blank check past the service panel. California C-46 is not a general contractor card. Arizona C-78 is liquid solar plumbing, not modules on a roof. Utah S202 is not automatic cover for every wire method on the job. California raised its licensing threshold from $500 to $1,000 in January 2025. Plenty of pages still print the old figure. Each Nevada license also carries a monetary limit. It caps what you can contract at one site or subdivision for one client. You can apply to the board for a one-project increase. Tell your agent which card and which invoice you actually bid.
Why Completed Operations and the Array Itself Still Matter
The leak or fault that shows up in October from a July hang is a completed operations question. Standard general liability is built to respond to injury or damage that happens during the policy period, including damage that appears after you leave. Some inexpensive installer policies restrict that grant. Ask where completed operations lives before you bind. Ask whether the aggregate is shared with the rest of the policy or stands on its own.
Competitors say general liability covers property damage. They skip the part that decides the redo. General liability typically excludes damage to the particular part of property you are working on. It also excludes property in your care, custody, or control. The modules you are setting sit in that gap. A loose clamp is often a job cost. Fire that ruins the attic is more likely a covered property damage claim. That split is the one that surprises people. Photograph the roof before you start. Write the invoice so it matches the class on the policy.
The modules sitting in the shop or on a truck are also a property story. Theft of staged inventory is usually inland marine or the installation floater, not the installer general liability. Confirm who buys that coverage before the first pallet leaves the warehouse.
How Much Does Solar Contractor Insurance Cost?
Price follows the class, the deductible, and the payroll, not a national average on a comparison site. A solo rooftop crew prices differently than a shop that sets commercial canopies across a warehouse roof. We do not invent a monthly teaser. Shop the language and the classification. A few thousand dollar callback usually sits inside the deductible. The insurance problem is still the class and the residential versus commercial split, not the size of that one array.
The stack around general liability moves the bill more than the GL number alone. Tools and equipment, commercial auto, the shop, and workers compensation are the lines that surprise people. Height work, a helper on payroll, and a multi-site commercial book all change the class. Request a quote and we will price the work you actually do.
Questions to Ask Before You Bind
Walk through these with your agent before the first certificate goes out.
1. What class did the carrier assign, residential rooftop, commercial, ground-mount, or a mix?
2. If you penetrate a roof or set a carport canopy, does the file show that exposure?
3. What happens to coverage when a solar job adds a service upgrade, battery storage, or an EV charger tie-in?
4. Does completed operations stay on after you leave the roof?
5. How does the policy treat damage to the modules you just set?
6. Are meters, torque tools, and spare modules scheduled on inland marine, and is there an installation floater for gear in transit?
7. Can the carrier issue the additional insured wording builders and general contractors actually ask for?
What Do General Contractors and Site Owners Require?
A certificate of insurance is evidence. It is not coverage. Most general contractors, builders, and site owners want about $1 million per occurrence and $2 million aggregate as a floor. They also want to be named as additional insured, plus a waiver of subrogation, plus primary and noncontributory wording. The endorsement has to exist. A certificate that promises wording the policy does not have is a problem waiting for a claim. Ongoing operations often use CG 20 10. Completed operations often use CG 20 37. Many jobs also ask for CG 25 03, the per project aggregate. We review the contract language and place the endorsements the job actually requires.
Local crews can start with the city pages that sit under this guide. Henderson crews, see Henderson solar contractor insurance. Valley crews, see Phoenix solar contractor insurance. San Diego County crews, see San Diego solar contractor insurance. Lehi and Utah County crews, see Lehi solar contractor insurance.
Push Back: I Only Do Residential Rooftops, So Why Carry All of This?
We hear this one a lot, and it deserves a straight answer. I only do residential rooftops, so the risk feels tiny. The exposure math says otherwise. One trip at a temporary edge, or a helper fall, is enough to generate a real claim. Beyond the raw risk, insurance is a sales tool in this trade. Builders, HOAs, and many homeowners require a certificate of insurance before you start. In Utah, the state requires general liability just to hold many licensed contractor classes. In California, a C-46 or C-10 card still needs workers compensation the moment you have help. Solo operators usually need less coverage than a ten person crew, not none.
Frequently Asked Questions
Do I need workers compensation if I work alone?
Nevada, Arizona, and Utah require it once you have employees. Utah also wants a Labor Commission waiver when you do not. A solo California specialty contractor can often still file an exemption until January 1, 2028, unless the qualifier is an RME. Confirm the class against the board’s current mandatory list before you assume an exemption applies.
Does general liability cover the modules I just set?
Usually no, not for damage to those modules. General liability typically excludes the part you are working on. Fire that ruins the attic is a different claim. The redo of your own hang is often a job cost.
Does an electrical card automatically cover solar installs?
The license family is often electrical or solar. The insurance class still has to match the invoice. A lighting-and-receptacle file may not have priced rooftop PV. Bid the array when the application names the array. The wrong class is a rating problem. It is not a magic void.
Is a homeowners policy enough for the installer?
Homeowners policies exclude business activity. Paid work on someone else’s roof will not find a home there. The truck between rooftops also sits outside personal auto once the carrier sees business use. Homeowners coverage for panels the owner already has is a separate file.
Can I get coverage with a prior claim?
Almost always, though the market may change. We can move a risk between standard carriers and specialty markets until the fit and the price both work.
How is this different from electrical contractor insurance?
Electrical contractor insurance is the full trade stack: service, lighting, panels, and commercial wiring. Solar contractor insurance is the installer GL file for photovoltaic work, including racking, roof penetrations, the shop, and the truck. Many operations need both conversations on one program. Start on the electrical guide when the book is broader than solar.
Ready to Compare Options?
Solar work rewards a clean invoice and an honest class. We shop your operation across a broad carrier lineup and match the policy language to the jobs you actually take. We pair general liability with the completed operations, tools, shop, and certificate wording this trade demands. If a residential rooftop book is growing into commercial canopies, we will say so before the certificate goes out. Request a quote and tell us about the work on your roofs, because we help businesses with their insurance needs all the time.


