
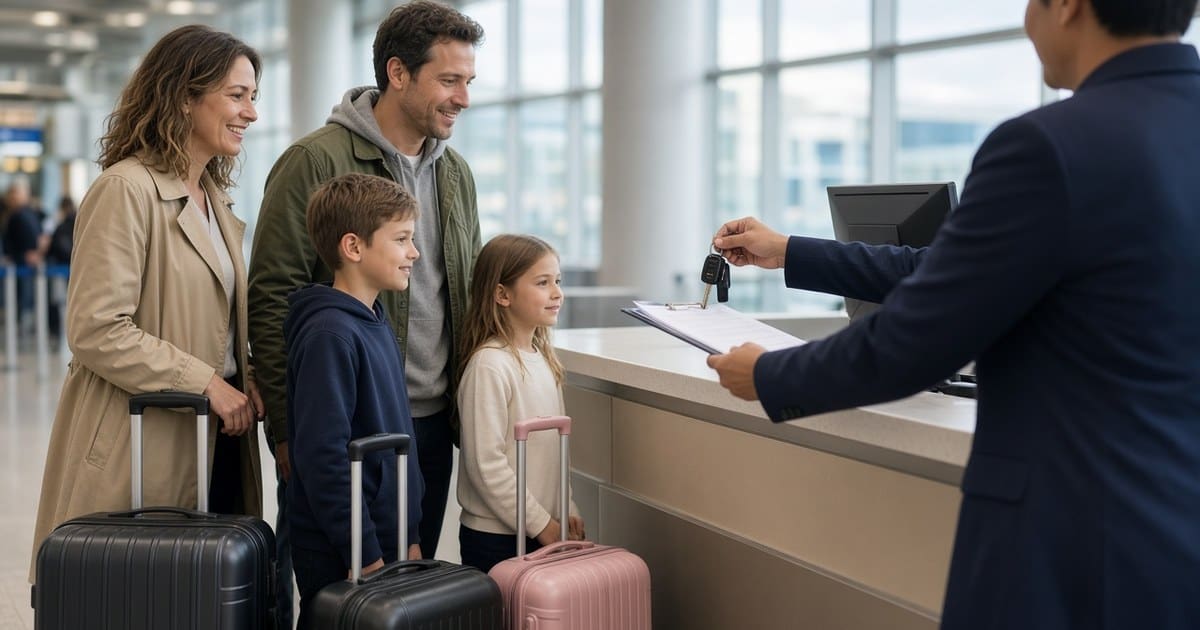
You step off a long flight with tired kids, and the rental agent slides over a contract that wants your initials in four places. Damage waiver. Extra liability. Personal accident. Belongings. Say yes to all of it and the bill climbs fast. Say no to all of it and you might be leaning on coverage you have never actually read. Most families guess, and since nothing usually goes wrong, the guess never gets tested.
This guide is about that moment at the counter. We will walk through what your own car policy usually carries over to a rental, where credit card benefits help and where they run out, what the rental company is really selling, and when buying it makes sense. It does not cover the rental car your policy pays for while your own car is in the shop. That is rental reimbursement, and our guide to what every car insurance coverage does explains it. Western Pacific Insurance is an independent agency serving drivers in Nevada, Arizona, California, and Utah, and we have local versions of this guide for Henderson, Phoenix, San Diego, and Lehi.
Your own auto policy comes first
If you own a car and carry full coverage, your personal auto policy is usually the first layer of protection on a rental. In many policies, the liability limits you chose for your own car extend to a rental you drive for personal use in the United States and Canada. If you also carry comprehensive and collision, many policies stretch those to the rental as well, with the same deductible you already pay. If you carry only liability, there is usually nothing in your policy that pays for damage to the rental itself.
Policies differ in the details, so read yours or ask us before you travel. A few questions are worth putting to us or your own carrier. Does my physical damage coverage apply to a rental, and is it capped at the value of my own car? Will the policy cover the rental company’s loss of use and administrative charges, or just the repair? Is there a limit on how many days in a row a rental is covered? Does it apply to a pickup, a large van, or a luxury car? Your answers will tell you how much of the counter menu you really need.
What the counter is selling
The collision damage waiver, often called a CDW or loss damage waiver, is not insurance. It is the rental company’s promise not to charge you for damage to or theft of its car, as long as you follow the rental contract. It tends to be the priciest item on the menu and the one most likely to overlap with coverage you already have. Its appeal is simplicity. With a valid waiver you can usually hand back the keys without filing a claim on your own policy, which keeps the claim off your record and spares you the deductible.
Supplemental liability protection adds liability coverage on top of the minimum the rental company carries or your own policy provides. Personal accident coverage pays medical and accidental death benefits for you and your passengers, which often overlaps with your health insurance and any medical payments coverage on your auto policy. Personal effects coverage pays for belongings stolen from the car, and homeowners and renters policies often cover those already, subject to their deductible.
Where credit card coverage falls short
Plenty of credit cards include a rental car damage benefit, and it can be worth having. Most of these benefits are secondary, though, which means they pay after your own auto insurance and usually pick up your deductible and some fees. A smaller number of premium cards offer primary coverage. Almost none include liability, so a card will not pay for the other driver’s car or anyone’s injuries.
To use the benefit, you typically have to book and pay for the entire rental with that card and decline the rental company’s damage waiver. Card benefits also commonly exclude certain vehicles, such as trucks, many vans, exotic and high-value cars, and antique cars. They cap how many days in a row the rental can run, often fewer inside the United States than abroad, and some countries are excluded altogether. Read your card’s benefit guide before you count on it. It is usually a separate document from your card agreement.
Loss of use and other surprise charges
After a crash, the rental company may bill you for more than the repair. Common extras include loss of use, which is the rental income it says it lost while the car sat in the shop, along with a diminished value claim, towing, storage, and an administrative fee. Some auto policies pay these charges and some do not, and card benefits vary too. Some states also limit what a rental company can collect from a renter, which is one reason we cover the local rules in our city guides.
Why liability limits matter even more on a rental
A rental often drops you into an unfamiliar city and an unfamiliar car, with heavy airport traffic around you and sometimes a car full of family or friends. If you cause a serious crash, the injury claims can far exceed state minimum limits. Your own liability limits usually travel with you, which is a good reason to carry higher limits at home. Many families pair those limits with an umbrella policy, which sits above your auto liability and, with many carriers, applies to rental cars you drive for personal use. Our guide to umbrella insurance cost and coverage shows how the layers fit together. An umbrella usually requires your auto policy to carry certain minimum limits underneath it.
When the rental company’s waiver is worth buying
Sometimes the waiver is the simpler choice. If you do not carry collision on your own car, there may be nothing else to pay for damage. If you are renting outside the United States and Canada, many personal auto policies do not follow you. If you are renting a large van, a moving truck, an exotic, or a luxury model, both your policy and your card may exclude it, and our guide to luxury and exotic car insurance explains how high-value cars are treated. And if a claim on your own policy would hurt your rates, or your deductible is high, paying for the waiver may be worth the peace of mind. Our guide to choosing an auto deductible can help you weigh that tradeoff.
Business trips, rideshare, and extra drivers
Personal auto policies are written for personal use. A car rented for your employer may be expected to fall under the company’s coverage instead, so check with your employer before you go, and see our comparison of personal and commercial auto insurance. Driving a rental for a rideshare or delivery app is another situation entirely. Most rental contracts restrict it, and our guide to rideshare and delivery driver insurance explains the gaps. Also put every person who will drive on the rental contract. A spouse, adult child, or friend who is not listed may void the rental company’s waiver, and some credit card benefits only cover drivers named on the contract.
Before you pick up the keys
- Call us or check your declarations page to see whether your liability, comprehensive, and collision coverage extend to rentals.
- Read your card’s benefit guide and note whether it is primary or secondary and which vehicles it excludes.
- Book and pay with the card whose benefit you plan to use.
- List every driver on the contract.
- Before you leave the lot, and again when you return the car, take photos or video of every panel, the windshield, the wheels, and the fuel and mileage readings.
- If there is a crash, follow our steps for what to do after a car accident, call the rental company, and contact us before you sign anything they send you.
If you would like to know what your policy carries over before your next trip, we can go through it with you and show where higher limits or an umbrella would help. You can learn more about personal auto insurance with us, or read how a claim works in our car insurance claim process guide.
We do not promise eligibility, rates, or availability, because those depend on the carrier, your driving record, and the policy you choose. Coverage terms, rental provisions, and credit card benefits vary by carrier and card issuer. Western Pacific Insurance helps drivers compare options. Have your current declarations page ready, then call 702-932-3105 or request a quote online.


