
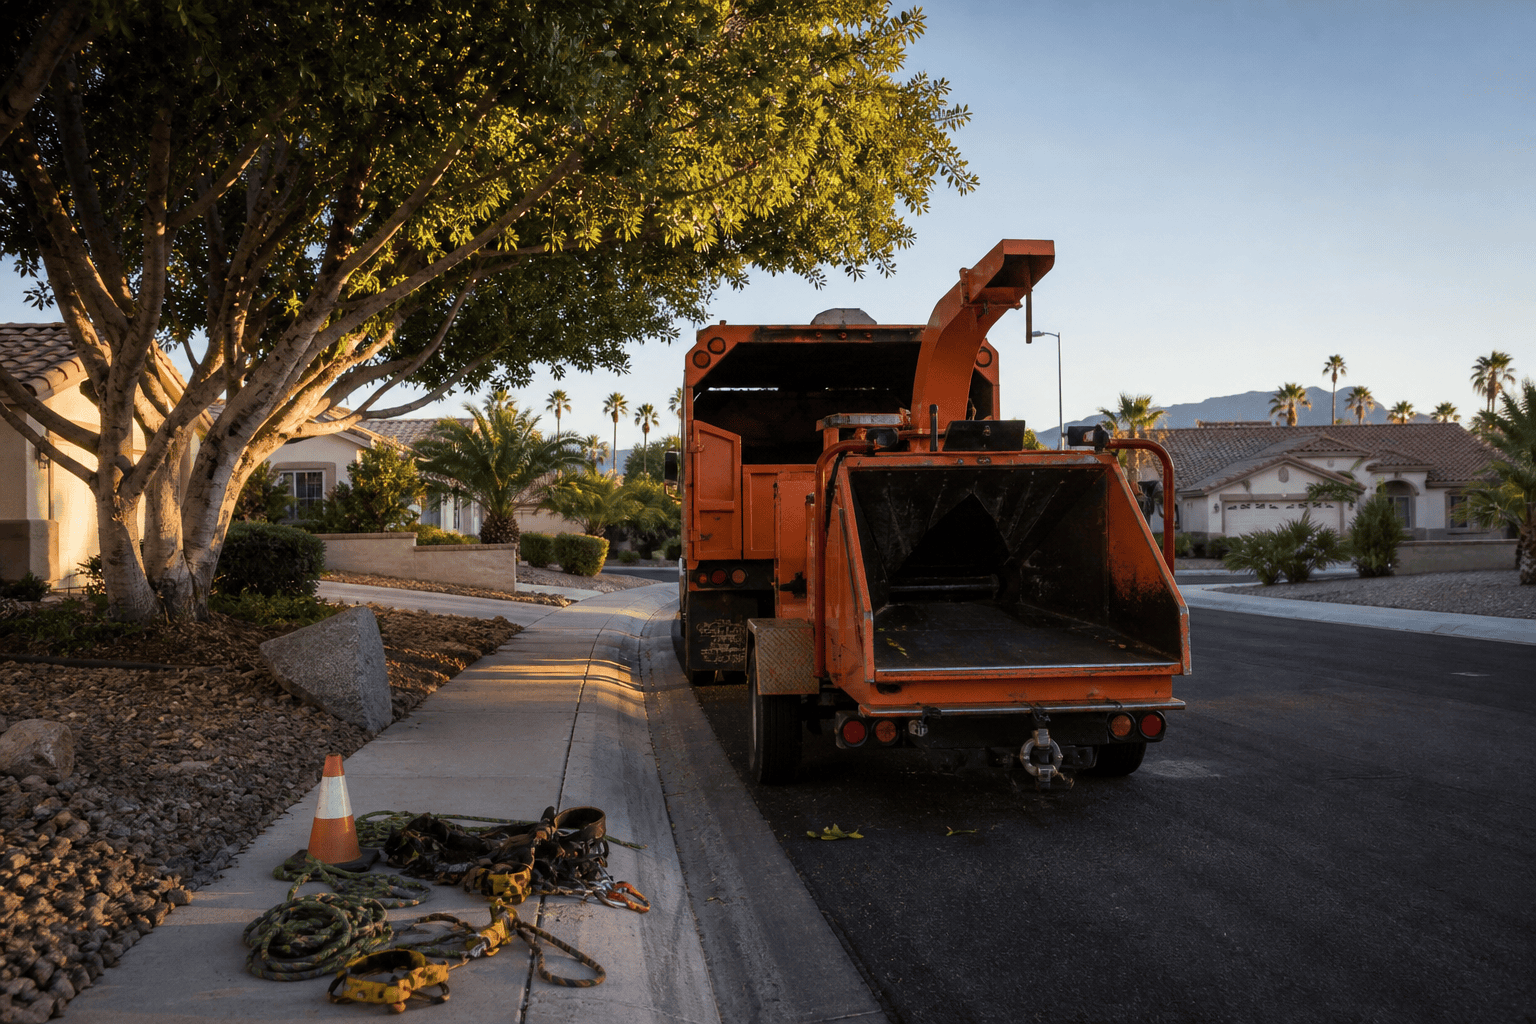
If you run a tree crew in Henderson, you already know the pattern. A property manager in Anthem or Green Valley calls about a removal, and before anyone touches a saw, they want a certificate of insurance on file. The campuses along Lake Mead Parkway and the HOAs off Stephanie Street go a step further. They want to see that the policy actually describes climbing and chipping, not a generic handyman policy with a magnet sign on a personal truck.
That is what Henderson tree service insurance is for. It covers the climber in the canopy, the ground crew feeding the chipper, and the truck and trailer running between jobs off the I-215. This post walks through each piece, explains where Nevada licensing fits, and tells you what we will ask when you request a quote. For the broader picture beyond Henderson, start with our tree service insurance guide.
The Certificate Usually Comes Before the Job
Most of the work you lose in Henderson, you lose on paper. Removals in Anthem and Green Valley tend to go through management companies that will not schedule you without a clean certificate. Some will also ask to be named as additional insured, and some want a specific limit before they sign. If your policy is written for general landscaping, the certificate may not say what they need to see, and you end up scrambling while a competitor gets the job.
The fix is simple but has to happen before you bid. Make sure your general liability is written for tree work, including climbing and removal, and that you can turn a certificate around quickly. An independent agency should be able to issue certificates the same day you ask, and we do that routinely for contractors across Henderson.
General Liability: When the Limb Lands Wrong
General liability is the core of the package. It responds when a limb, a falling section of trunk, or your work in general damages someone else’s property or injures someone who is not on your crew. In practice, that means the roof in Seven Hills, the block wall between two Green Valley Ranch backyards, or the parked car on a Stephanie Street cul-de-sac.
Two things matter more for tree crews than for most trades. First, the classification on the policy needs to reflect what you actually do. Trimming, removal, and climbing carry a different exposure than mowing and irrigation, and carriers price them differently. If your policy was quoted as landscaping and you are dropping 40-foot pines, that gap can become a problem at claim time. Second, larger jobs often involve equipment near structures, power lines, and neighboring lots, so you want limits that give you room rather than the smallest number a form will accept.
If your business also does lawn care, weed control, or spraying, that side of the operation belongs in a different conversation. We cover it in our post on Henderson landscaping contractor insurance.
Workers Compensation for Climbers and Ground Crew
Once you have employees, workers compensation belongs in the package. Climbing is one of the more dangerous jobs in the trades, and the ground crew working around a chipper is not far behind. Workers compensation pays for medical care and lost wages when someone on your crew is hurt on the job, and it protects the business from the lawsuit that often follows a serious injury.
Be honest about your headcount and how you pay people. Crews that grow from two guys to six over a busy spring sometimes forget to update the policy, and the audit at the end of the year catches it. Property managers along Lake Mead Parkway will also usually want workers compensation shown on the certificate, and some will refuse a certificate that lists an exemption.
Commercial Auto for the Chipper Truck
A chipper truck with a trailer behind it is a commercial vehicle, and a personal auto policy is not built for it. Commercial auto covers the truck, the trailer it pulls, and the liability if the rig causes an accident on the way from an Anthem job to a Green Valley job. It also matters when an employee is driving, which is common on tree crews and often excluded under personal coverage.
List every vehicle that goes to a job site, including the crew pickup and any dump trailer. If you sometimes drive a personal vehicle for business, or an employee drives their own truck to pick up parts, ask us about hired and non-owned auto coverage so that exposure is not left hanging.
Inland Marine for Chippers, Saws, and Climbing Gear
Your equipment is your income, and most of it lives on a trailer rather than in a building. Inland marine, sometimes called equipment coverage, protects chippers, stump grinders, saws, ropes, harnesses, and climbing gear whether they are on the job, in transit, or sitting in the yard. Theft from a job site or a locked trailer is the claim we see most often on this coverage.
Keep a simple list of your gear with serial numbers and rough replacement values. The chipper is the big line item, but the saws and rigging add up fast, and an accurate schedule makes both the quote and any future claim go smoother.
Nevada Licensing and Where Tree Work Fits
Nevada does not have a dedicated tree specialty license class. The closest fit is the C-10 landscape contractor classification, and NAC 624.280 describes that scope as including the planting and maintaining of trees. The Nevada State Contractors Board has said that tree removal and trimming on their own do not require a license, while planting does. Large felling jobs can still raise scope questions with the Board, so if your work is expanding, it is worth confirming directly with them where your operation lands.
ISA arborist certification is voluntary in Nevada. It is not a licensing requirement, but some commercial clients and HOAs value it, and it can help when you are competing for the bigger campus and association contracts. From an insurance standpoint, the important part is that your policy accurately describes the work, whether or not you hold a C-10 or an ISA credential.
What We Will Ask When You Quote
To quote tree service insurance in Henderson correctly, we need a clear picture of the operation. Expect questions like these:
- What share of your work is trimming, removal, and climbing versus lawn or irrigation work
- Whether you climb, use a bucket truck, or both, and how high you typically work
- How many employees you have and how they are paid
- Every vehicle and trailer that goes to a job site
- A list of major equipment, especially chippers and stump grinders
- Whether your clients ask for specific limits or additional insured wording on certificates
Answering these up front lets us match you with a carrier that actually writes tree work, rather than one that will quote low and cancel after the first inspection.
Get a Henderson Tree Service Quote
Western Pacific Insurance is an independent agency based in Henderson, and we work with tree and landscape contractors across the Las Vegas valley. Start with a Nevada quote request, tell us about your crew and your equipment, and we will put together general liability, workers compensation, commercial auto, and inland marine that a property manager will accept the first time.


