
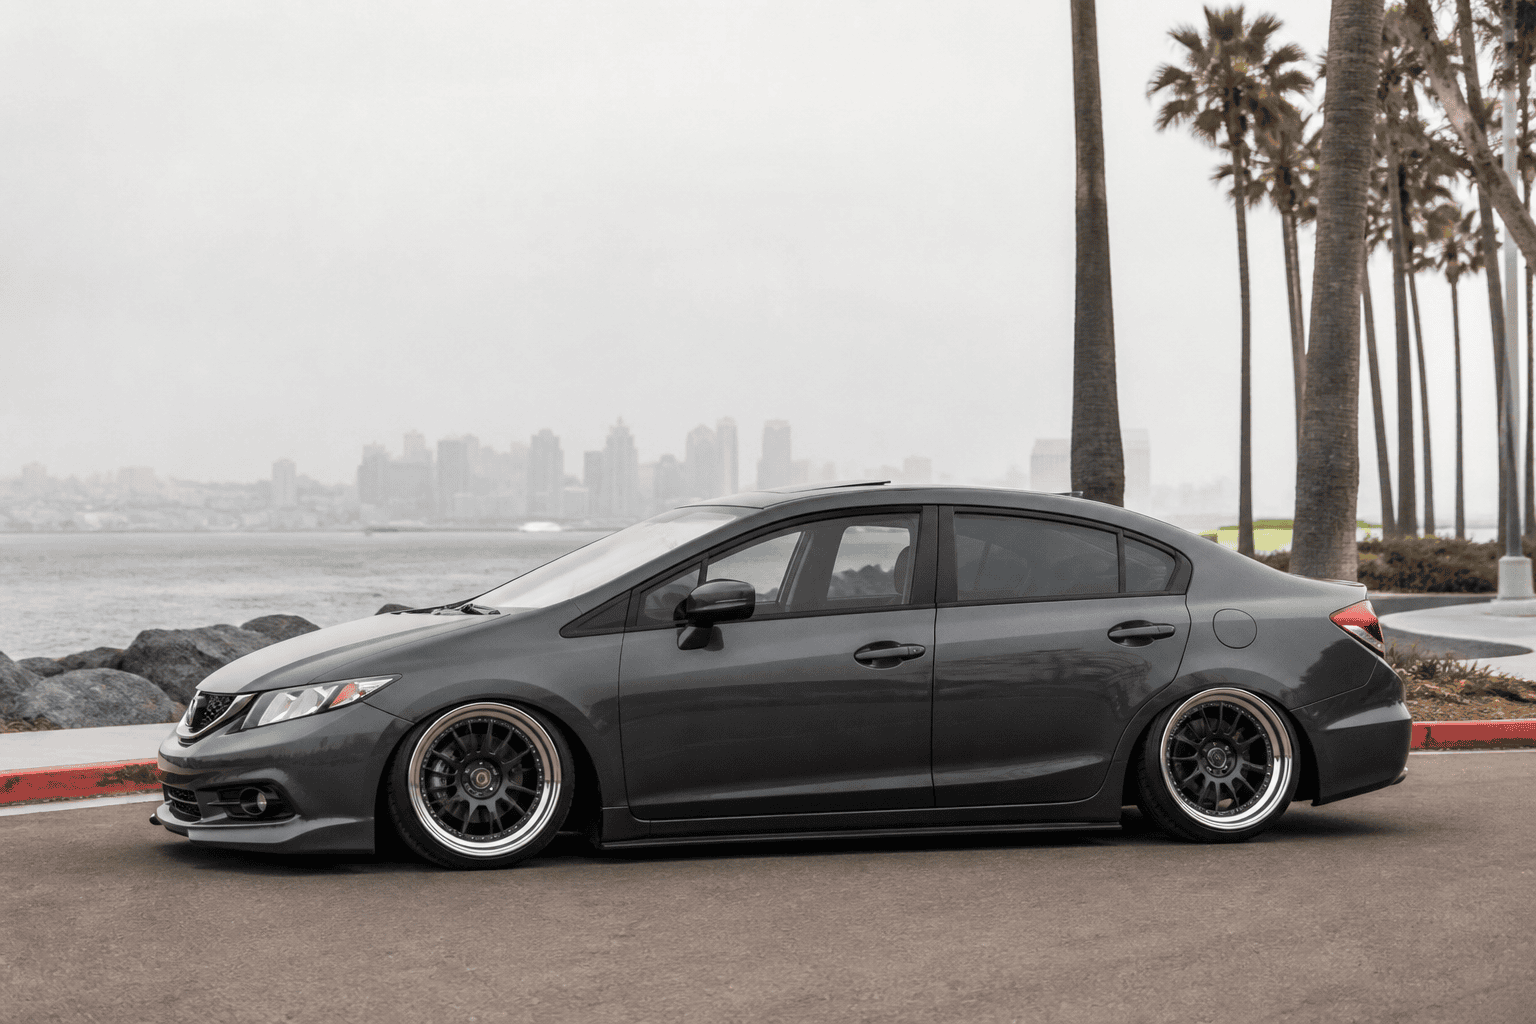
San Diego Modified Car Insurance: Lowered Cars and Daily Builds
On January 1, 2024, California made it legal again to drive a car whose body sits lower than the bottom of its wheel rims. Assembly Bill 436, written by a San Diego assemblymember, repealed the old ride-height rule and ended local cruising bans. That included the ordinance that kept lowriders off Highland Avenue in National City for thirty years. The law finally caught up with a car culture that runs from Chicano Park to Kearny Mesa, but your auto policy probably has not. San Diego modified car insurance closes that gap, so the suspension, wheels, and paint you paid for are on the policy before you need them.
This guide is for the car you actually drive to work. If yours is a limited-use collector, our classic car insurance page is the better starting point.
Street Legal and Fully Insured Are Two Different Questions
AB 436 changed what an officer can cite you for, and it did nothing to change how an insurance company values your car. A standard auto policy starts from the vehicle the factory built. It pays collision and comprehensive claims at actual cash value, which is the market price of a comparable stock car. A 2019 Civic on coilovers and forged wheels is still a 2019 Civic on paper. Unless the policy says otherwise, a total loss pays for the stock car and leaves the build unpaid. Our modified car insurance guide walks through that math in detail.
California adds one more layer. Emissions-related parts need a California Air Resources Board Executive Order number to be legal on a smog-controlled car. An engine swap also has to pass a state referee inspection. Carriers ask about both, because a swapped or tuned car is a different risk than a bolt-on car. A swap you disclose up front is a quoting conversation. The same swap discovered by an adjuster is a claim problem.
What San Diego Modified Car Insurance Should Cover
The base of the policy is the same for every driver: liability, uninsured and underinsured motorist coverage, collision, and comprehensive. California raised its minimum liability limits to 30/60/15 in 2025, the first increase since 1967. Those numbers are still a floor, since a single late-model SUV costs far more than $15,000 to replace. You take on no risk by carrying more liability than you end up needing, only by carrying less. That is why we quote limits well above the state minimum.
Your build sits on top of that base through custom parts and equipment coverage. It is an endorsement that adds your aftermarket parts to the collision and comprehensive coverage you already carry. Many policies include a small built-in amount for custom equipment, and one set of wheels and tires can use all of it. Set the limit from your receipts and include labor, because installation is a real share of what the build cost. When you are between two limits, choose the higher one. Paint, wraps, air ride, hydraulics, audio, seats, and lighting all count toward that total, along with suspension and wheels.
Where San Diego Is Hard on a Build
Most of the claims we see on lowered cars come from three local conditions, and each one points to something you can do now.
The first is parking structures. The ramps in Mission Valley, UTC, and downtown garages are steep at the transitions, and they catch splitters, side skirts, and oil pans. A cracked lip may fall inside your deductible, but a crushed oil pan or a bent subframe will not. That larger claim is where scheduled parts matter. Towing matters there too, because a wheel-lift truck can damage a car that needed a flatbed. Tell your agent if the car sits that low, so your roadside coverage fits the car.
The second is street parking. Plenty of builds in North Park, Pacific Beach, and Barrio Logan sleep at the curb. A wheel set that looks great on Instagram also looks great to a thief. Comprehensive coverage pays for stolen parts that appear on the policy. It has a much harder time with parts nobody documented, so dated photos and receipts are worth the ten minutes they take.
The third is salt air. Aftermarket control arms and exhaust parts corrode faster in Ocean Beach or Point Loma than they would inland. No auto policy covers rust or wear, so treat corrosion as maintenance. Keep your photos current so they show the car as it sits today.
Historical Plates Are Not a Workaround
Owners of older builds sometimes look at California historical vehicle plates and collector policies as a cheaper route. The California DMV issues those plates to vehicles built after 1922 that are at least 25 years old and of historic interest. It also limits them to vehicles driven primarily for exhibitions, parades, and club activities. A 1964 Impala that comes out for Chicano Park Day and weekend cruises can fit that description. An agreed-value collector policy is often the better product for that car. Our guides to classic car insurance agreed value and California classic car insurance cover it.
A 1998 Integra that commutes to Sorrento Valley five days a week is a different story. It is old enough for the plate, but it does not fit the use. Collector policies carry their own expectations about mileage and storage, and most assume you own a separate daily driver. If you drive the car to work, insure it as a daily driver on a standard auto insurance policy with the parts scheduled.
What to Bring to the Quote
A good quote on a modified car depends on what you can show us, so it helps to gather a few things first:
- A list of every modification, with the brand and the approximate installed cost
- Receipts for parts and labor, even partial ones
- Dated photos of all four sides, the engine bay, the interior, and the wheels
- The ride height, and whether the car needs a flatbed
- Whether emissions parts carry an Executive Order number, and whether a swap has its referee label
- Your annual mileage and where the car parks overnight
Get a San Diego Quote
Western Pacific Insurance is an independent agency licensed in California, and we place coverage for daily-driven modified cars across San Diego County. Because we work with a range of carriers, we can take your build to the companies that want it instead of forcing it onto one form. Start with a California quote request and tell us what you have bolted on. You can also visit our California insurance page to see everything we write in the state.


