
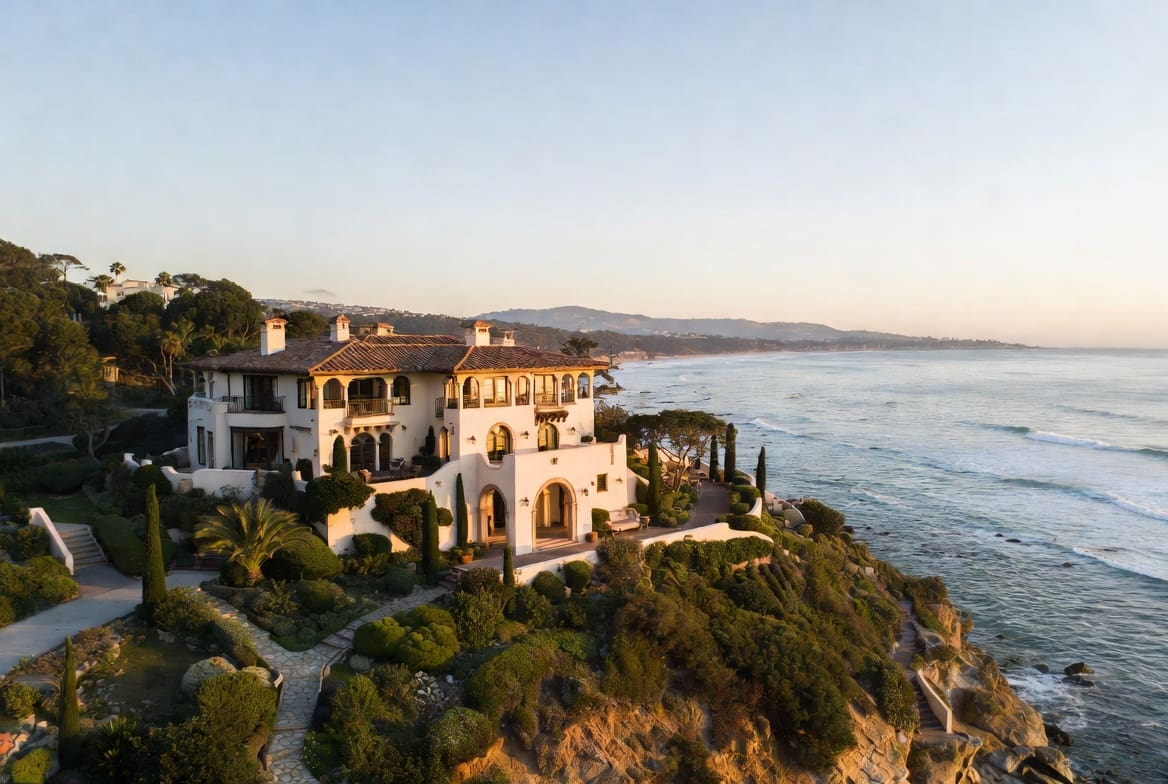
If you own a home in La Jolla, Rancho Santa Fe, or Del Mar, you may have already gotten the letter. The non-renewal notice, or the premium increase that reads like one. California’s market has tightened hard, and in wildfire-exposed areas some owners of million-dollar-plus homes find their choices narrowing. This guide explains how high-value home insurance works for San Diego owners. It also covers why non-renewal is a signal rather than a crisis. And why an independent agency that shops the whole market, standard and private-client alike, is your best route to a real option.
Why San Diego’s luxury market is the hardest to place
San Diego combines the two things high-value carriers price most carefully: extreme home values and wildfire exposure. Coastal luxury in La Jolla and Del Mar runs from the mid seven figures into eight figures on the oceanfront. Inland estates in Rancho Santa Fe carry prices in the millions with sprawling custom construction on equestrian acreage. Many sit in or near wildfire zones, the exact risk that has driven standard carriers to non-renew across California.
When a standard carrier drops a home like this, the FAIR Plan alone isn’t the answer. Sometimes another standard carrier will write it; often, especially in wildfire zones, the private-client carriers are the better fit. Carriers like Chubb, PURE, and AIG Private Client Select offer open-perils contents, guaranteed or extended replacement cost, blanket scheduling for art and jewelry, and high liability limits. They also have appetite for risks the standard market is shedding. An independent agency shops both sides for you.
The California non-renewal and FAIR Plan gap
Here’s the piece that trips people up. California’s FAIR Plan is the fallback for homes carriers won’t write. But the California FAIR Plan caps residential coverage at $3 million per location, below what many San Diego luxury homes need. It’s also a bare-bones named-peril fire policy, not full homeowners coverage. For a high-value home, a private difference-in-conditions policy usually wraps the FAIR Plan. That wrap adds back liability, theft, and water damage, and raises limits to match the home. Structuring it correctly is specialized work, and it’s exactly what an independent agent with high-value carrier access handles.
What California requires, and why it doesn’t help here
California doesn’t require homeowners insurance by law. Lenders require enough to cover the loan, which on a coastal estate can fall far below rebuild cost. So the state and the lender both leave the real question unanswered: can this home actually be rebuilt after a total loss? In wildfire country, that’s the question that matters most.
Building high-value coverage in San Diego
For San Diego luxury owners, we start by getting the home in front of the carriers that still write in your area and ZIP. Appetite shifts by wildfire exposure, so we check current appetite first. Where a home needs the FAIR Plan, we structure the difference-in-conditions wrap so no gaps remain. We run a true replacement cost estimate reflecting coastal or hillside construction, schedule valuables under blanket coverage, and layer excess liability. As an independent agency licensed in California, we shop the whole high-value market. The coverage mechanics are in our guide to high-value home insurance, and the rebuild-cost detail in extended vs. guaranteed replacement cost.
My San Diego home was non-renewed. What now?
Non-renewal is common here, and it signals you belong in the high-value market, not a dead end. Depending on the home and its wildfire exposure, that means a private-client carrier or a FAIR Plan policy wrapped with a private difference-in-conditions policy. We place exactly these situations.
Can I still get guaranteed replacement cost in California?
Some high-value carriers still offer it, though it has grown selective in wildfire zones. We check current carrier appetite for your address. Where guaranteed coverage isn’t available, we structure the strongest extended replacement cost the market will offer.
Own in La Jolla, Rancho Santa Fe, or Del Mar? If your San Diego home clears roughly $1 million to rebuild, let us review it. Start a California high-value home quote, or visit our California insurance page.


