
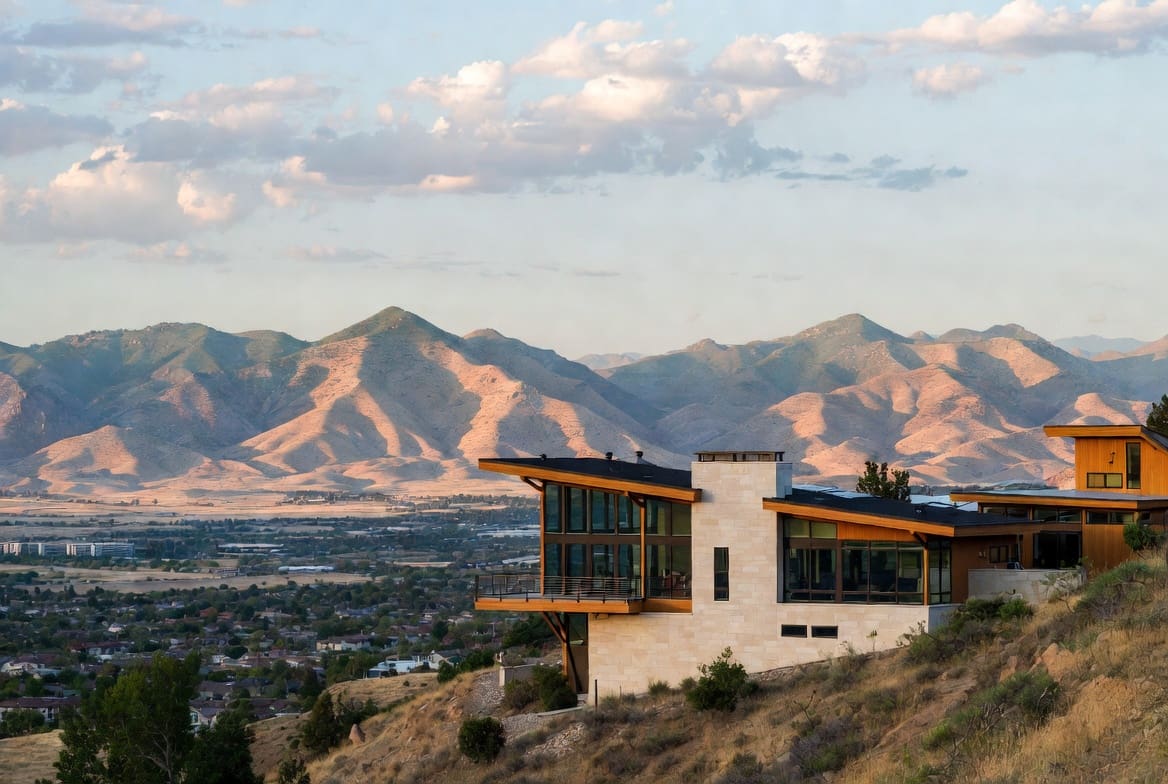
Lehi’s high end does not look like Beverly Hills, and that is exactly why it gets mishandled. The custom homes on the Traverse Mountain benches, the executive builds funded by Silicon Slopes money, and the view lots over Utah Valley clear the threshold where a policy needs a careful look. Yet they are often written like ordinary tract homes, with the dwelling limit set too low. This guide explains how high-value home insurance works for Lehi and Utah County owners, and why an independent agency that shops the whole market beats the carrier on the billboard.
Why Lehi’s luxury tier gets underinsured
Lehi grew fast, and its upper end grew with it. Tech executives at Adobe, Oracle, and other Silicon Slopes employers have built and bought custom homes on Traverse Mountain and along the benches. Many have finished walkout basements, large square footage, and high-end finishes. Two things go wrong in the mass market. First, the dwelling limit gets set from the builder’s or purchase price, not the true cost to reconstruct a custom home at retail rates in a tight Utah County labor market. That’s exactly the rebuild-cost-versus-market-value gap the Insurance Information Institute warns leaves homeowners underinsured. Second, valuables sit under standard sub-limits, so a watch collection or art is barely covered.
Homes over $1 million have real options. Standard carriers with high-value programs write well past $1 million. National General’s Premier program, an Allstate company, goes up to $5 million, and for many Lehi homes that’s the competitively priced fit. When a home has a large collection, a very high rebuild cost, or a hard-to-place risk, the private-client carriers fit better. Chubb, PURE, and AIG Private Client Select add richer forms: open-perils contents, guaranteed or extended replacement cost, blanket scheduling for valuables, and high liability limits. An independent agency compares both.
What Utah requires, and why it doesn’t help here
Utah doesn’t mandate homeowners insurance. Lenders require enough to cover the loan, which for a high earner with a small mortgage can fall far below rebuild cost. Neither the state nor the lender verifies that a custom Traverse Mountain home can fully reconstruct. That responsibility sits with you and your agent.
Building high-value coverage in Lehi
For Lehi luxury owners, we start with a true replacement cost estimate. It includes finished basements and custom finishes. It also reflects the reality of rebuilding one home at retail rates while Utah County’s crews are booked on new subdivisions. Then we schedule valuables under blanket coverage and layer excess liability to fit the household. As an independent agency serving Utah County, we shop every high-value carrier at once rather than defend one company’s answer. The full coverage breakdown is in our guide to high-value home insurance, and the rebuild-cost mechanics in extended vs. guaranteed replacement cost.
My Lehi home is newer. Isn’t the builder’s coverage estimate accurate?
Usually not for a rebuild. Builders price at volume across many homes. Reconstructing your single custom home after a loss happens at retail rates with a tight local labor pool. That gap is how newer high-end homes end up underinsured, and a proper replacement cost estimate corrects it.
Does Lehi really have good high-value options?
Plenty. Standard carriers with high-value programs write many Utah homes over $1 million. Private-client carriers like Chubb, PURE, and AIG Private Client Select handle homes with collections, tough rebuilds, or hard-to-place risks. We match your home to the carrier whose program fits it best rather than force it into one company’s box.
If your Lehi or Utah County home clears roughly $1 million to rebuild, let us take a look. Start a Utah high-value home quote, or visit our Utah insurance page. We serve Lehi and all of Utah County.


