
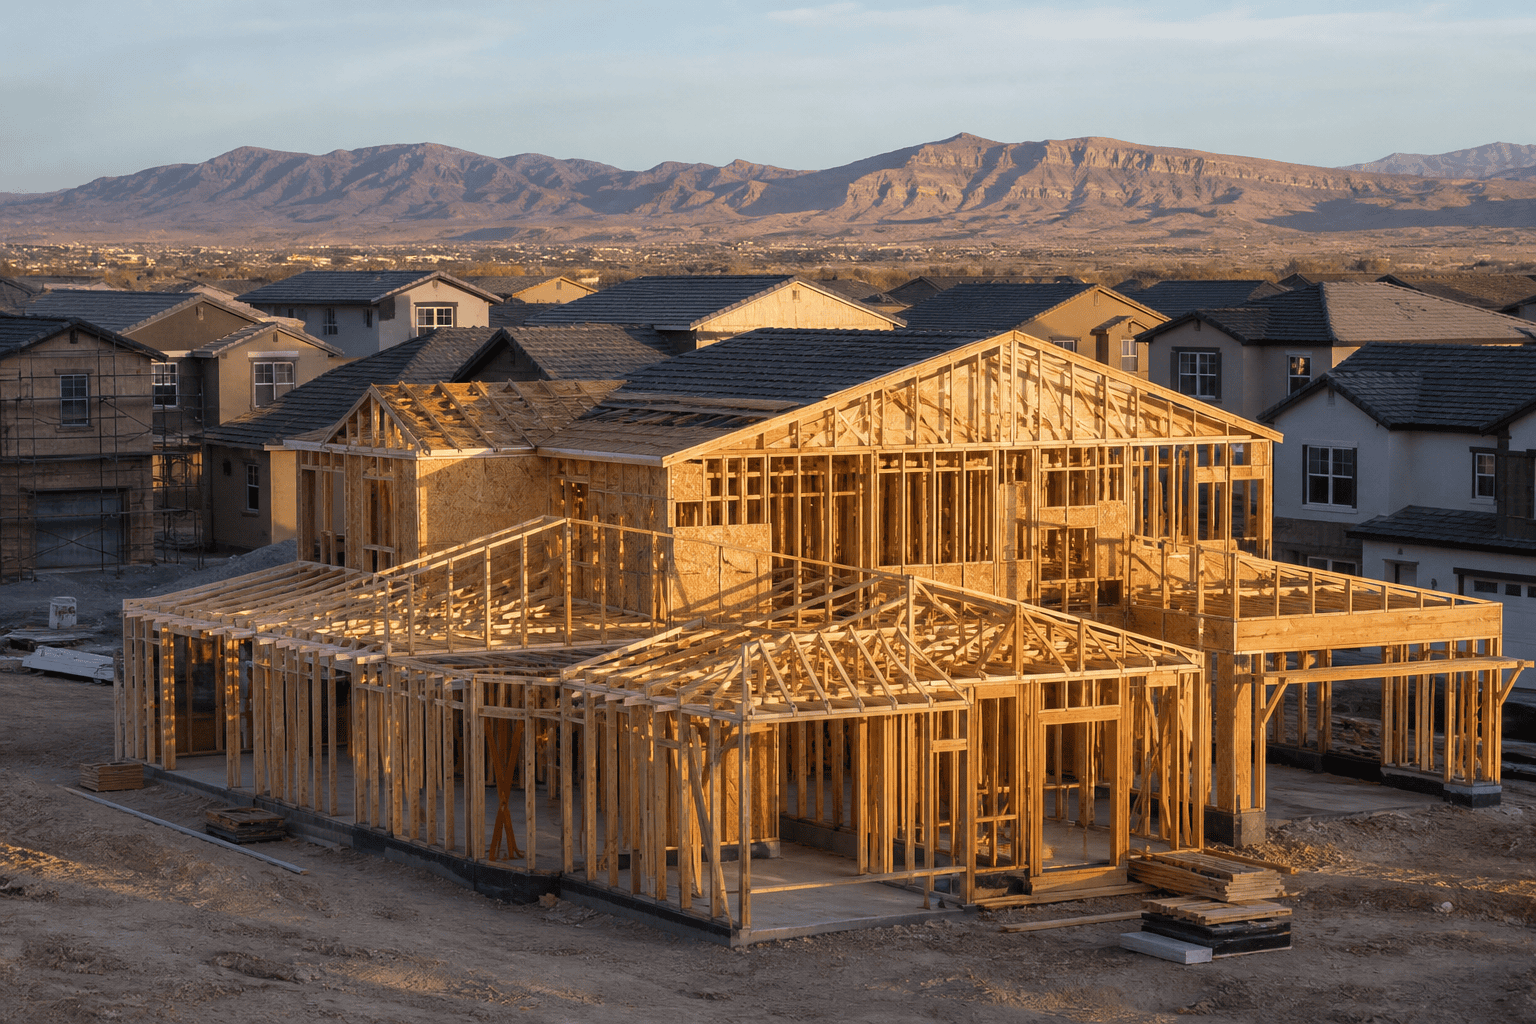
Henderson Framing Contractor Insurance: What Your Crew Actually Needs
Drive through Cadence, Inspirada, or West Henderson on a weekday morning and you will see the same thing on lot after lot. A framing crew has two or three weeks to stand walls, set trusses, and sheath a roof before the next trade shows up. If that is your crew, Henderson framing contractor insurance comes down to three questions. Does your liability policy actually cover new residential work? Is your payroll sitting in the right workers comp class? And who pays when the wind takes down what you stood yesterday? This guide walks through each one, plus the Nevada license rules that decide which jobs you can sign.
What Henderson Framing Contractor Insurance Includes
A framing program has four core pieces. General liability pays when your work injures someone outside your crew or damages property that is not yours. It is the policy every builder asks about first. Workers compensation covers your own people, which matters more in framing than in almost any other trade because the injuries are falls and nail guns. Commercial auto covers the trucks and trailers, and an inland marine policy covers the tools, compressors, and equipment that ride in them.
Most production builders in the valley write a minimum liability limit into the subcontract. Treat that number as the floor. There is no downside to carrying more limit than a contract asks for, and one serious injury on a two-story frame can run past a basic limit quickly. That is why an umbrella over the liability and auto policies is worth pricing every time. Our framing contractor insurance guide covers the full program in more depth, including what happens to your policy class when roof work joins the invoice.
Check Your Liability Policy for Residential Exclusions
This is the part that catches Henderson framers, and it has nothing to do with price. Nevada gives homeowners ten years after substantial completion to bring a construction defect claim, a window the Legislature extended from six years in 2019. Carriers know that, so many contractor liability forms, especially the cheaper ones, exclude new residential construction, tract housing, or condos and townhomes outright. A framer working Inspirada production lots on one of those policies has a certificate the builder accepted and no coverage behind it.
Ask your agent to show you the exclusions page, not the declarations page. While you are there, confirm that your builder’s additional insured endorsement covers completed operations and not only ongoing work. Defect claims arrive years after you pull off the lot. If a builder enrolls you in a wrap-up program, your own policy will usually exclude that project. You still need it for every job outside the wrap.
Workers Comp: The Class Code Drives the Price
Nevada requires workers compensation once you have employees, and the Contractors Board expects proof of it. What you pay depends heavily on classification. Residential framing up to three stories generally rates under NCCI code 5645, commercial and taller work under 5403, and interior trim under the much cheaper 5437. If your crew does both framing and finish, keep the payroll records separate by job. When they are blended, the auditor puts every dollar in the highest rated class.
The same audit looks at your subs. Piece-rate crews and labor subs who cannot produce their own certificate land on your payroll after the fact. That bill arrives months after the job money is spent. Collect certificates before anyone steps on the deck.
Summer adds one more item. Nevada OSHA began enforcing its heat illness regulation in April 2025. Employers with more than 10 employees must complete a job hazard analysis and, where heat exposure exists, add water, rest, cooling, training, and emergency procedures to their written safety program. Underwriters ask for that written program, and having it ready makes your submission stronger.
Nevada’s C-3a License and Your Monetary Limit
The Nevada State Contractors Board licenses structural framing under the C-3 carpentry classification. NAC 624.210 defines subclassification C-3a, Carpentry and Repairs, as form work, framing, and rough carpentry, including subflooring, siding, exterior stairs, roof decking, truss members, and sheathing. C-3b is finish carpentry, which is a different exposure that we cover in Nevada carpenter insurance. Make sure your insurance application describes the work the same way your license does. A policy written for finish carpentry does not want to hear about a framing crew at claim time.
Every Nevada license also carries a monetary limit. It caps what you can take on for one client on a single site or subdivision. A framer licensed at $250,000 cannot sign a $900,000 multi-lot package, and builders do check the Board’s license lookup. The Board sets your bond between $1,000 and $500,000 based on that limit and your financials. Residential contractors also pay into the Residential Recovery Fund. The Board does not require general liability to hold the license. Your builders will, in every subcontract you sign.
When the Wind Takes Down an Open Frame
Spring wind and summer monsoon outflow can rack or drop walls that are braced but not yet tied together with trusses and sheathing. General liability will not pay you to rebuild your own work. It responds to what your falling wall hits, such as the neighbor’s block wall or the plumber’s truck. The structure itself usually belongs on the project’s builders risk insurance in Henderson, which the builder or owner carries. Read your subcontract to see whether subs are covered under it and who absorbs the deductible. An installation floater can fill the gap by covering your materials and labor until the builder accepts the work.
Truss day deserves its own conversation. A crane hired with an operator is a different exposure than a telehandler you rent bare. Physical damage to rented equipment is not covered by your liability or auto policy unless you add it.
Tools, Trailers, and Lumber on the Lot
Schedule your tools and equipment at this week’s replacement cost, not what you paid five years ago. Commercial auto covers the truck and trailer but not the nailers and saws inside them. A break-in on a job street is an inland marine claim. Tell your agent if lumber packages get dropped ahead of your crew or sit on the lot overnight. Who owns that material, and when ownership changes hands, decides whose policy responds to a theft.
Get a Henderson Quote
Western Pacific Insurance is headquartered here in Henderson, and we place coverage for framing contractors across the valley. As an independent agency, we shop your operation with carriers that actually write new residential framing, and we match the classification to the jobs you take. Bring your license number and monetary limit, your payroll split by type of work, and the insurance requirements from a recent subcontract.
Start with a Nevada quote request, or visit our Nevada insurance page to see everything we write in the state. If you run the whole site and not only the frame, see Henderson contractors insurance and Henderson general contractor insurance.


