Water damage comes in many forms: pipes burst, appliances overflow, roofs leak, plumbing freezes, the list goes on. But there’s one kind of water damage that catches homeowners and renters off guard more than any other, because they assume they’re covered when they’re not. If a sewer or drain backs up into your home, or your sump pump fails and overflows, a standard insurance policy typically won’t pay a dime. That’s where water backup coverage comes in.
Also written as water back-up coverage or water back up coverage, and sometimes called “water back-up and sump overflow” coverage, it’s one of the most useful and inexpensive add-ons you can put on a home or renters policy. Below, we cover what it protects, what it doesn’t, what it costs, and how to decide whether you need it.
What is water backup coverage?
Water backup coverage is an optional endorsement — an add-on — for water damage to a home that results from a backed-up sewer, drain, or sump pump. This coverage is not included in most standard homeowners insurance policies but can be added on. Water backup coverage limits and deductibles vary from policy to policy.
When a covered backup happens, the coverage can help pay to repair or replace both the structure of your home and the belongings inside it — flooring, drywall, cabinets, furniture, electronics, clothing, and appliances like a washer, dryer, or furnace in the affected area — plus professional cleanup and water removal, up to your selected limit and minus your deductible.
What water backup coverage does NOT cover
This is where people get tripped up, so it’s worth being precise. Water backup coverage does not pay for:
- Flooding. Water that enters from outside — rising water, storm surge, an overflowing wash or retention basin — is flood damage, which requires separate flood insurance (usually through the NFIP). This matters in Nevada, where flash flooding during monsoon season is a real risk.
- The sump pump itself. If your pump breaks, water backup coverage pays for the water damage it caused, but not to replace the broken pump. That’s what equipment breakdown coverage is for.
- Maintenance issues or negligence. Wear and tear, a drain you knew was clogged, or a pump you forgot to turn on generally won’t be covered.
Same fixture, two different claims
Here’s where it gets confusing. The same toilet can produce two completely different claims depending on what caused the overflow. If a clog inside your home’s plumbing causes a toilet to overflow, that’s a standard homeowners claim — the source is internal, and the damage to your floors and walls is typically covered. But if the city sewer line backs up and pushes sewage through that same toilet, the damage may look identical, yet the source is different. That’s a water backup claim, and without the endorsement, you’re paying for the entire cleanup yourself.
The source of the problem — not the symptom — determines which coverage applies.
Why do I need water backup coverage?
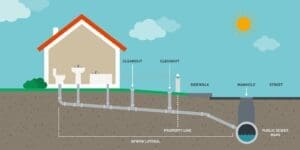
As a homeowner, you are responsible for maintaining the sewer lines between the city’s sanitary main and your home. This area is known as the sewer lateral, as shown in the graphic below. (The Insurance Information Institute has a helpful overview of what homeowners are responsible for.)
According to the Civil Engineering Research Foundation, the number of backed-up sewers increases by about 3% each year. Yikes! Some of the common causes of backed-up sewers include deterioration over time (on average, sewer systems are about 30 years old), tree roots that cause damage to sewer lines, sanitary main blockages, and pipelines that combine stormwater and sewage.
Backed-up sewers can be a problem for anyone, no matter where you live. If you decide to go without this add-on coverage, you are taking a risk. It can get quite pricey to pay for water removal, sanitation, floor cleaning/replacement, electrical repairs, and personal property replacement if this happens to you.
Do renters need water backup coverage too?
Yes — and this is one of the most overlooked gaps in renters insurance. A standard renters policy protects your belongings, but it carries the same water backup exclusion a homeowners policy does. If you rent a basement apartment, a ground-floor unit, or anywhere a sewer or drain backup could reach your things, your furniture, electronics, and clothing are exposed unless you add water backup coverage to your renters policy.
The building’s owner insures the structure, but their policy does nothing for your property inside the unit. For a few dollars a year, a renters water backup endorsement closes that gap. If you rent, ask specifically whether your policy includes it — most don’t by default.
How much does water backup coverage cost, and how much do I need?
It’s one of the most affordable endorsements you can buy. Coverage limits commonly start around $5,000 and go up to $25,000 or more per occurrence. When you consider that a serious sewer backup can cause tens of thousands of dollars in damage, the math tends to favor the coverage.
How much you need depends on what’s at risk: where your equipment and belongings sit (a finished basement, a garage with a furnace and water heater, or a ground floor full of possessions all raise your potential loss), how old your home and sewer lateral are, and what it would cost to restore the lowest, most vulnerable level of your home. When in doubt, we can help you estimate the right limit.
Watch the sublimit on your policy
Even if you have water backup coverage, the limit might not be enough. Many policies cap water backup at $5,000 or $10,000 — and a real sewage remediation can cost far more than that. Some carriers offer higher limits of $15,000, $20,000, or even $25,000, and the cost to raise your sublimit is usually small. A few dollars a month can make a significant difference in a real claim. Ask your agent one question: what is my water backup sublimit, and can I raise it?
Who needs to pay closest attention?
Every homeowner should know whether this endorsement is on their policy, but some homes carry more risk than others:
- Homes with basements. Basements have the lowest drains and openings, so that’s where backup water shows up first. A finished basement full of furniture, electronics, and storage makes the financial exposure much worse.
- Older homes with clay or cast iron sewer laterals. Those materials crack and deteriorate over time, making the lateral more likely to fail in a way that leads to a backup.
- Homes in areas with aging municipal systems or frequent heavy storms. Combined sewer systems that handle stormwater and sewage together can get overwhelmed during downpours.
What can I do to minimize my risk?
Luckily, there are some things you can do to help keep your sewer lines flowing properly. The Insurance Information Institute gives some great suggestions, including:
- Do not put grease down the drain- it will solidify later on and cause blockages in the sewage system. Instead, you should pour grease into a container until it cools off, then throw it away in the trash.
- Properly dispose of paper products such as feminine hygiene products, paper towels, and diapers. Do not flush them!
- If you have trees on your property, have a professional cut back the roots occasionally.
- Disconnect your sanitary sewer from French drains, sump pumps, or other flood control systems. (It is also illegal to have these types of connections).
- Consider installing a backwater prevention valve so sewage can only go out and not back in.
Even if you take all these precautions, there are always factors outside your control. Therefore, we recommend adding water backup coverage to any homeowners or renters policy.
What kind of water damage is included in a standard homeowners policy?
If water damage occurs suddenly and accidentally, a standard homeowners insurance policy will usually cover it. An example of this would be a washing machine supply hose breaking and water leaking everywhere. An insurance adjuster will determine whether or not the peril is covered.
Water backup coverage in Nevada, Arizona, Utah & California
Requirements and risks vary by where you live, and we write this coverage across all four states we serve. For specifics in your area, see our dedicated guides:
- Nevada Water Backup Coverage
- Arizona Water Backup Coverage
- Utah Water Backup Coverage
- California Water Backup Coverage
Do you have additional questions?
If you have more questions about water backup coverage or want to add it to your home or renters policy, give us a call at 702-932-3105. We can also help you determine how much water backup coverage you need. As an independent agency, we shop multiple carriers across Nevada, Arizona, Utah, and California to find you the right coverage at the right price.


