
Replacement cost vs. actual cash value is one of those insurance details that almost never comes up until something breaks, burns, floods, or gets destroyed. At that point, the difference isn’t theoretical — it’s the difference between getting back to normal or writing a very large check out of pocket.
This applies to both personal insurance and business insurance. Homeowners, landlords, contractors, office owners, and multi-location businesses all run into this issue, often without realizing which valuation method their policy is actually using.
In the accompanying YouTube video, we walk through how this plays out in real situations. This article goes deeper — with more examples, more nuance, and a clearer look at the tradeoffs involved.
What replacement cost and actual cash value really mean in practice
Most people hear “replacement cost” and assume it means the insurance company pays whatever it costs to replace the damaged item. And they hear “actual cash value” and assume it just means “less money.”
That’s directionally correct, but incomplete.
Replacement cost is about restoring functionality. The goal is to repair or replace the damaged property with something of like kind and quality, without subtracting for age or wear. Actual cash value starts with that same replacement cost, then subtracts depreciation based on age, condition, and useful life.
The key point is that both methods start with the same replacement cost number. The difference is what happens next.
How this shows up in a homeowner claim
Take a simple example. Your roof is fifteen years old. A storm damages it badly enough that it needs to be replaced.
If your home insurance is written on a replacement cost basis, the carrier calculates what it costs to install a comparable new roof today. You’ll still have a deductible, but depreciation is not permanently taken out of the claim.
If the policy is written on an actual cash value basis, depreciation is deducted and never recovered. A roof halfway through its expected life might only be paid at fifty percent of replacement cost. The damage is covered, but the valuation method quietly shifts a large part of the cost back onto you.
This is why two neighbors with similar homes can have wildly different claim outcomes from the same storm.
You can learn more about how homeowners policies are structured on our home insurance page, or explore the broader context on our personal insurance overview.
Why actual cash value is more common than people realize
Actual cash value is often used intentionally in certain situations. Older homes. Rental properties. Secondary structures. Policies designed to keep premiums down.
The issue isn’t that ACV is “bad.” The issue is when the policyholder doesn’t realize that’s what they have.
We routinely see claims where the damage itself is covered, but the check is far smaller than expected because depreciation was quietly built into the policy. That surprise usually shows up after the adjuster’s estimate is finalized — not when the policy is purchased.
How this plays out in commercial property insurance
The stakes are often higher on the business side.
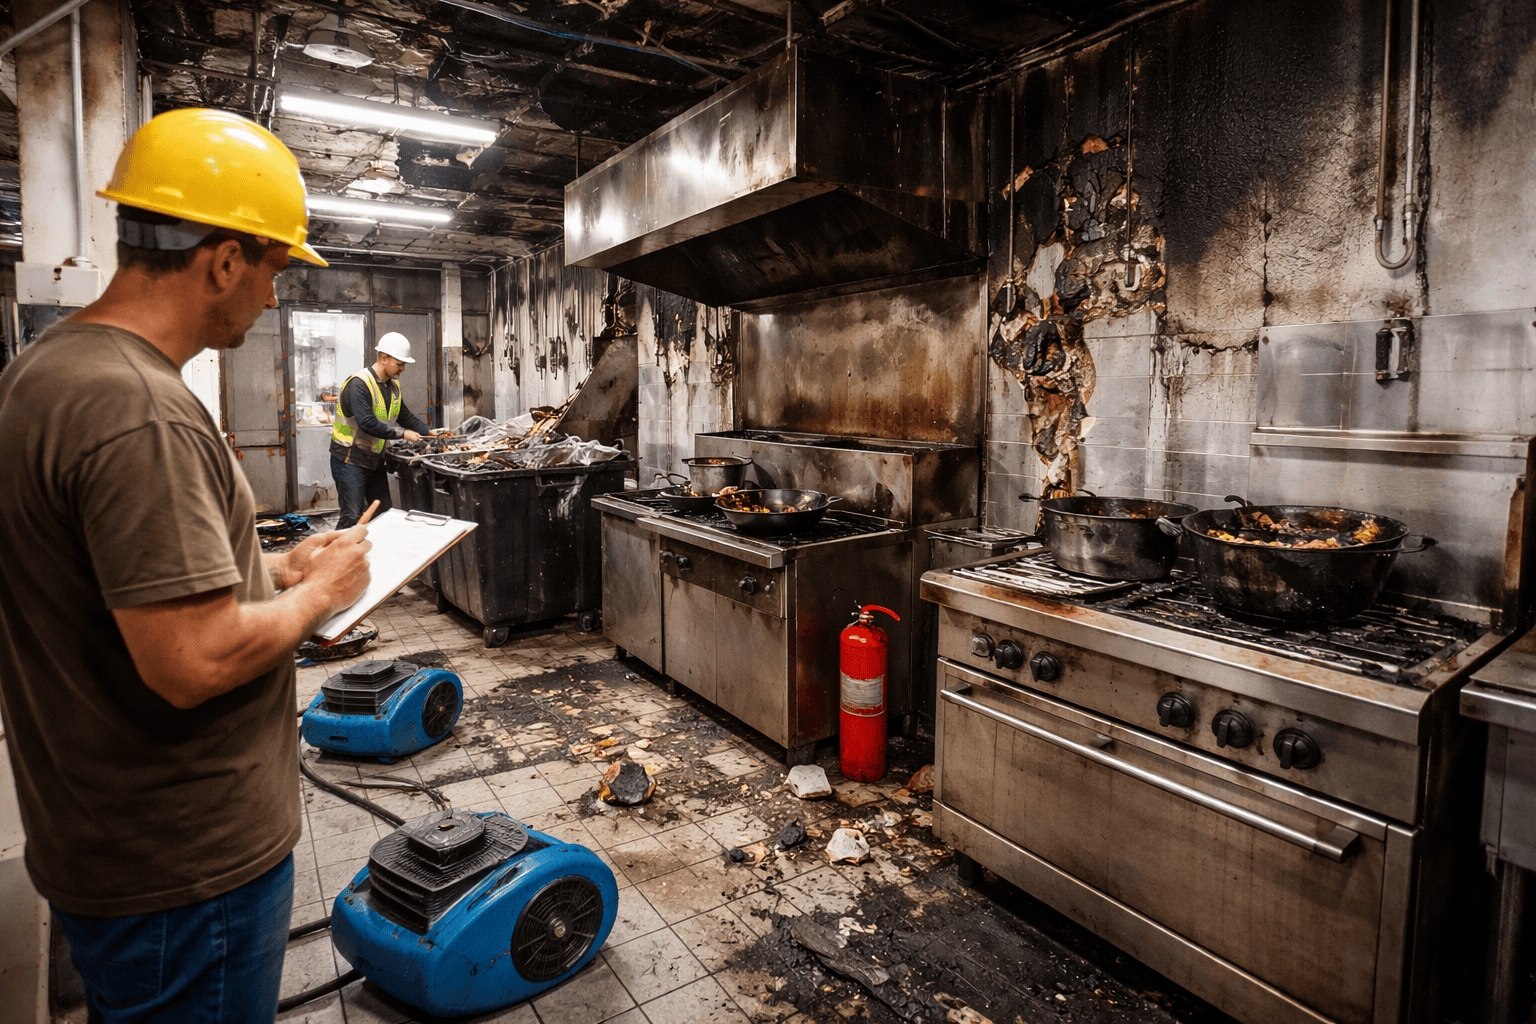
Imagine a small warehouse, retail space, or contractor yard with older improvements, shelving, or specialized equipment. A fire or water loss damages part of the building and the contents inside.
If the policy is written on a replacement cost basis, the intent is to get the business operational again with comparable equipment and build-out. If it’s written on an actual cash value basis, depreciation can dramatically reduce the payout — even though the business still needs functional replacements to reopen.
This is one of the most common valuation gaps we see in commercial claims.
You can read more about how these policies are structured on our commercial property insurance page, or review the broader landscape on our business insurance overview.
Why insurers care about valuation methods
From an insurer’s perspective, replacement cost and actual cash value represent different risk profiles.
Replacement cost assumes the property will be maintained and restored to a functional standard. Actual cash value recognizes aging assets and transfers part of that aging risk back to the policyholder.
Neither approach is inherently wrong. The problem arises when the valuation method doesn’t match the financial reality of the person or business buying the policy.
The mistake most people make when choosing coverage
The most common mistake is optimizing for premium without understanding valuation.
A policy with an attractive price can quietly rely on actual cash value in key areas — roofs, contents, equipment, or outbuildings. Everything looks fine on paper until a loss happens and depreciation shows up on the estimate.
This is why valuation deserves its own conversation, separate from deductibles and limits.
How to think about replacement cost vs. actual cash value the right way
The right question isn’t “Which one is better?”
The right question is “If this were damaged tomorrow, how would I actually pay to replace it?”
If the honest answer is “I’d expect insurance to handle most of it,” then replacement cost usually makes sense. If the answer is “I’d be okay absorbing part of that cost to keep premiums lower,” then actual cash value may be a reasonable tradeoff.
This applies whether you’re managing a household or running a business.
Industry perspective and independent resources
The National Association of Insurance Commissioners provides a neutral explanation of how replacement cost and actual cash value work from an industry standpoint, which you can review here: Replacement Cost vs. Actual Cash Value — III.
How this ties back to the video
If you haven’t watched the YouTube video yet, it walks through real claim scenarios where this distinction changes the outcome in very practical ways. This article is designed to supplement that explanation with more detail and broader context.
Many viewers find it helpful to read through this first, then watch the video with a clearer framework in mind.
Final thoughts
Replacement cost vs. actual cash value is not a technical footnote. It’s a financial decision with real consequences.
If you’re not sure how your home or business is valued today, that’s worth clarifying before something happens — not after.


