
Nevada homeowners liability coverage is the section of your policy that protects you when someone is injured at your home. It is part of Section II of your homeowners policy. Whether you live in Henderson, Las Vegas, Reno, or anywhere else in the state, your liability coverage matters every time a guest walks through your door or steps into your backyard.
Coverage E and Coverage F in Nevada
Your homeowners policy includes two liability coverages. Coverage E is personal liability. It pays damages when you are found legally responsible for someone’s injuries. It also covers your legal defense costs. Coverage F is medical payments to others. It pays for minor guest injuries without requiring fault. The Nevada Division of Insurance consumer guide to home insurance walks through the main coverages in a standard policy.
Coverage F limits are typically $1,000 to $5,000 per person. A neighbor trips on your front walkway and needs an X-ray. Coverage F can handle that without anyone determining who was at fault. Coverage E limits typically start at $100,000 and can go up to $500,000. When injuries are more serious, Coverage E is the financial backstop that matters.
Nevada Negligence Rules and Premises Liability
Nevada follows a modified comparative negligence standard. An injured person can recover damages as long as they were less than 50% at fault for their own injury. If a guest at your home slips on a wet floor and they were partially responsible – maybe they ignored a warning or were not paying attention – their damages would be reduced by their share of fault. But they can still recover.
Property owners in Nevada owe a duty of care to invited guests. That duty includes maintaining the property in a reasonably safe condition and warning guests about known hazards. A broken step, a loose railing, an icy driveway you did not salt – all of these can form the basis of a premises liability claim.
Dog Bites and Nevada’s Breed Protection Law
Nevada was one of the first states to pass a law prohibiting insurance carriers from using breed as a factor in underwriting decisions. Senate Bill 103, passed in 2022, prevents carriers from refusing to issue, canceling, or increasing premiums based solely on a dog’s breed. Carriers can still ask about a dog’s behavioral history – bites, dangerous or vicious designations – but they cannot use breed itself as a reason to deny or restrict coverage.
Nevada evaluates dog bite liability under common law negligence. There is no strict liability statute for dog bites. The question is whether the owner was negligent in controlling the animal. After a bite, carriers may still surcharge, exclude the dog, or nonrenew the policy based on the dog’s individual history.
Pools and Trampolines in the Nevada Climate
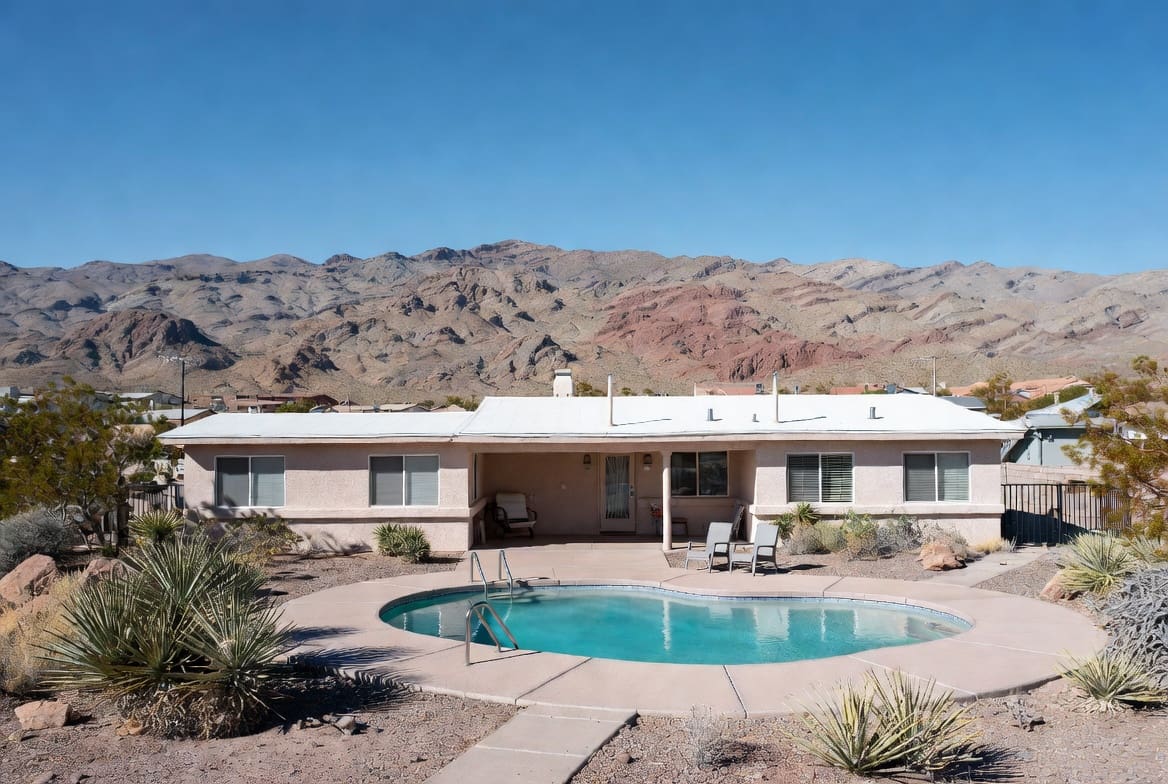
Nevada’s climate makes backyard pools a common feature. Pools and trampolines are attractive nuisances. If a child is drawn onto your property and injured, you may face liability exposure even if the child was not invited. Carriers often require fencing with self-latching gates and other safety features. Make sure your carrier knows about any attractive nuisances on your property.
Umbrella Policies for Nevada Homeowners
Standard liability limits may not be enough if a serious injury occurs at your home. A personal umbrella policy adds $1 million or more in additional coverage. It sits on top of both your homeowners and auto liability. For Nevada homeowners with pools, dogs, or a full backyard entertainment setup, an umbrella is worth the conversation with your agent.
Western Pacific Insurance is based in Henderson, Nevada. We write homeowners coverage across the state. If you want to review your liability limits, get a Nevada quote today. Learn more about our Nevada coverage.


