
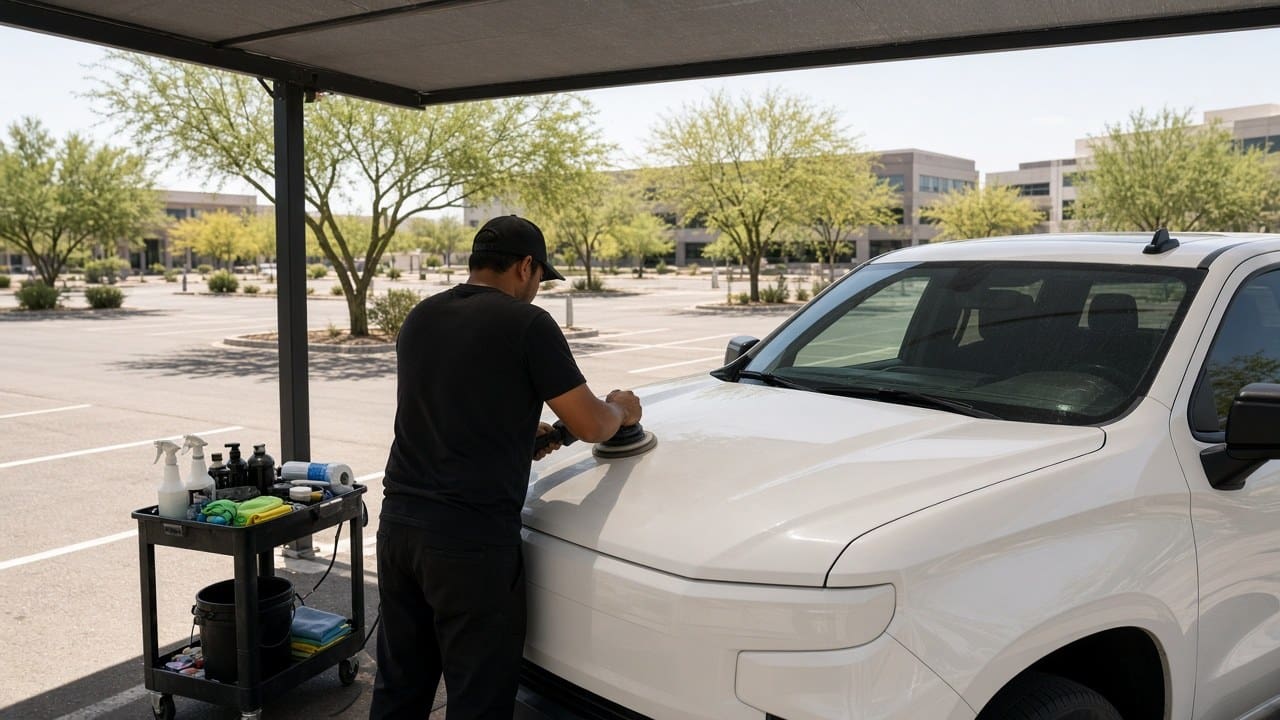
By mid-morning in July, a black truck’s hood on an Arcadia driveway gets hot enough to flash-dry a spritz of water before you can wipe it off. That’s the reality Phoenix detailers work around every day. You chase shade, start before sunrise, and move panel by panel because the Valley’s heat will ruin a paint job faster than almost anywhere else in the country. It also changes what your insurance needs to cover, in ways owners in milder climates rarely have to think about.
This page focuses on what’s specific to Phoenix. For the full picture on coverage types and how mobile detailing insurance works in general, see our mobile detailing insurance guide.
Who you’re working for, and what they’ll ask of you
A typical Valley route might run from a driveway in Arcadia to an office park in Tempe to an employee lot along the Chandler Price Corridor. Dealer and fleet accounts add another layer entirely. Those contracts almost always spell out insurance requirements before you’re allowed on the property, and the bigger the account, the more specific the ask. Expect requests for additional insured status, a waiver of subrogation, and higher liability limits than you’d carry for residential work alone. Read those contracts closely before you sign, because the coverage has to be in place before the first visit, not after.
Heat, monsoon dust, and other people’s paint
Hot panels change how compounds and polishes behave, and water spots etch into paint faster in direct Arizona sun than almost anywhere else. After a monsoon rolls through, cars show up coated in grit that will scratch the clear coat if you rinse it wrong. All of that raises the odds that a customer’s car gets damaged while it’s in your hands.
Here’s the coverage gap that catches new detailing businesses off guard: a standard general liability policy generally excludes damage to property in your care, custody, or control. That’s exactly the risk you’re carrying every time you touch someone else’s paint. Garagekeepers coverage is built to fill that gap, and it’s not optional for this business. When you’re comparing quotes, ask how the coverage triggers, what the deductible looks like, and whether the limit actually matches the vehicles on your route. A dealer lot detailer working on $80,000 trucks needs a different limit than someone doing weekly washes in a residential neighborhood, and it’s worth setting that limit higher than you think you need rather than cutting it close.
The heat affects your crew too. Arizona’s workers’ compensation law applies to employers with employees regularly working in the business, and heat illness, slips, and lifting injuries show up often in this trade. Water breaks, shade structures, and schedules built around avoiding the worst hours of the day protect your people, and a business that takes heat safety seriously is also an easier business to insure.
Phoenix’s runoff rules
Phoenix regulates what can go into the storm drain system under City Code Chapter 32C. The ordinance does allow some residential car washing as a conditional discharge, but that exception is written for homeowners washing their own vehicles in their own driveway, not for a business washing cars for pay. If you’re operating commercially, plan on containment and reclaim, and know exactly where your wastewater is going before you start a job. Standard general liability policies generally exclude pollution claims, so if your operation runs through a lot of chemicals, ask your agent about adding pollution coverage as a separate line.
Coverage most Phoenix detailing businesses carry
| Coverage | What it covers |
|---|---|
| General liability | Third-party injury or property damage, like a slip on a wet walkway or overspray drifting onto a neighbor’s car |
| Garagekeepers | Damage to a customer’s vehicle while it’s in your care |
| Commercial auto | Your rig and any trailers, plus hired and non-owned auto coverage if employees use their own vehicles for work |
| Inland marine | Equipment that lives on the rig, which in Phoenix usually means generators and water systems running hard in the heat |
| Workers’ compensation | Required once you have employees |
| Umbrella | Higher limits when a contract asks for more than your base policies provide |
See our business auto insurance page for more on how commercial auto works for a mobile rig.
Licensing in Arizona
The Arizona Registrar of Contractors licenses construction trades, and detailing is cosmetic work, not construction, so ROC licensing doesn’t apply here. You’ll still need standard state and local business registration. If your crew also does pressure washing on driveways, storefronts, or fleet yards, that’s a different insurance conversation. See our Phoenix pressure washing insurance page for what changes when you add that service.
Getting a quote
Before you call, pull together your revenue by type of work, the most expensive vehicles you regularly service, payroll, vehicle and trailer details, equipment values, and any insurance requirements a contract has already sent you. Western Pacific Insurance places detailing coverage across Arizona, Nevada, California, and Utah.
Call 702-932-3105 or request a quote online.


