Hair salon insurance protects your business from the claims and losses that come with running a salon. If you own a salon, manage booth renters, or are thinking about opening one, understanding what your policy actually covers is the first step toward avoiding expensive surprises.
General Liability Is Not the Whole Story
Most salon owners start with general liability insurance. That covers things like a client slipping on a wet floor or a stylist knocking someone’s phone off the counter. It handles bodily injury and property damage on your premises.
But general liability alone may not cover claims that come from the services you provide. A client who suffers chemical burns from a color treatment or an allergic reaction to a product is making a professional service claim. That type of claim falls under professional liability, sometimes called errors and omissions coverage. If your policy only has general liability, you could be paying out of pocket for a service-related lawsuit.
What a Business Owners Policy Covers
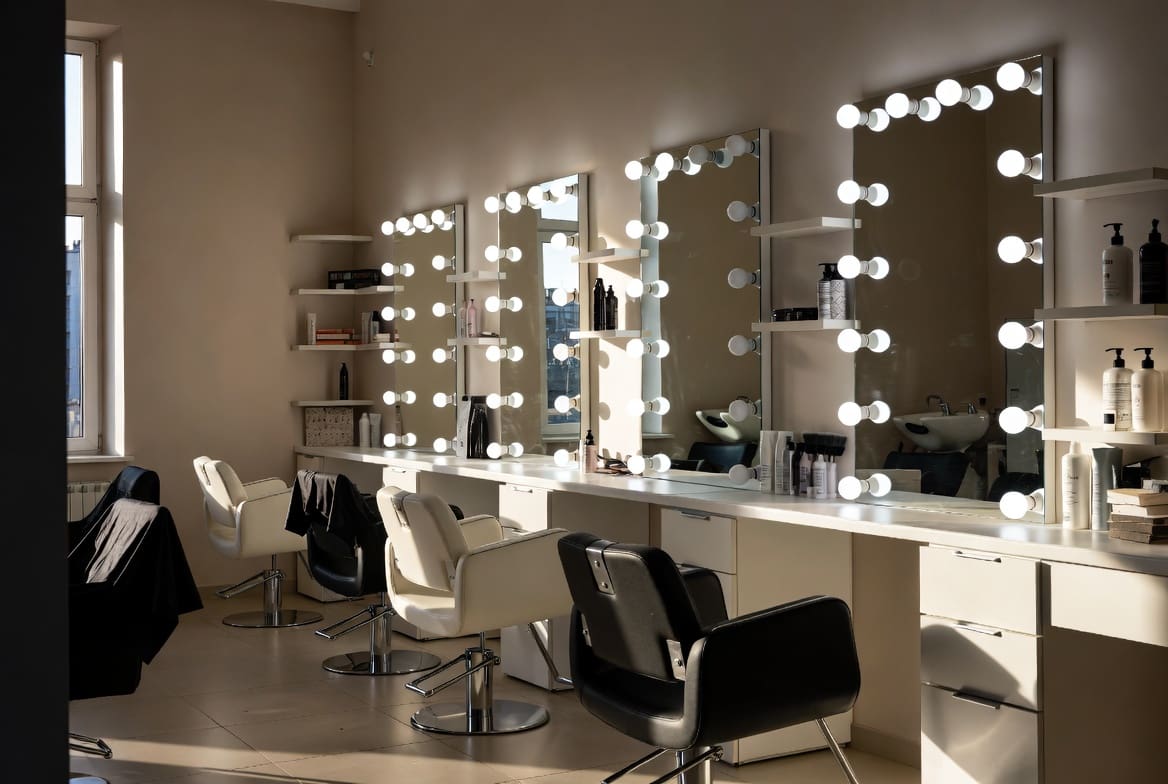
A business owners policy bundles general liability with commercial property coverage. For salon owners who lease or own a space, this is typically the foundation of the insurance program. The property piece covers your equipment – styling chairs, mirrors, wash stations, dryers, and product inventory.
Business income coverage is often built in as well. If a pipe bursts and floods your salon, business income helps replace the revenue you lose while the doors are closed.
One area that gets overlooked is tenant improvements and betterments. A salon buildout can be expensive. Plumbing for wash stations, flooring, lighting, and custom finishes may not be fully covered unless the policy accounts for them. Do not just insure the products on the shelf and forget the money you spent building the space.
A business owners policy does not automatically include professional liability. That is often a separate endorsement. Make sure it is there before you assume you are covered for service-related claims.
Workers Compensation for Salon Employees
Stylists work with chemicals every day. Hair color, bleach, relaxers, and keratin treatments all carry risk. A stylist who develops chemical burns on her hands or respiratory issues from product fumes is filing a workers comp claim. Repetitive motion injuries are common too – shoulder problems, wrist injuries, and carpal tunnel from years of cutting and styling.
Slips behind the chair also happen regularly. Salon floors are hard surfaces with water and product on them constantly. Workers comp covers the medical bills and a portion of lost wages for all of these situations.
If you have employees and do not carry workers comp, you are exposed to significant penalties in most states. Do not assume booth renters, 1099 workers, or part-time workers are automatically outside the workers comp conversation. That is a state-specific classification question.
The Booth Renter Coverage Gap
A booth renter is a licensed beauty professional who rents a chair or station from you and operates independently. When structured correctly, they are not your employee. They are running their own business inside your space.
Your insurance policy is designed to cover your business. It is generally not designed to cover the booth renter’s business. If a booth renter’s client has an allergic reaction to a product the booth renter chose and applied, that claim is the booth renter’s responsibility.
But if the booth renter does not carry their own coverage and the injured client sues, the client’s attorney is going to name the salon and the salon owner along with the booth renter. Even if the claim is ultimately the booth renter’s responsibility, you may still have to defend yourself.
Require every booth renter to carry their own general and professional liability coverage. Get a certificate of insurance before they start. Have the lease agreement require them to name you as an additional insured where the policy allows it, especially on the general liability side.
Other Coverages Worth Asking About
Inland marine coverage, sometimes called tools and equipment coverage, protects portable business property. Professional shears, hot tools, clippers, and styling equipment can add up to thousands of dollars. This matters most for booth renters and mobile stylists whose personal gear is not covered under the salon’s property policy.
Cyber liability is relevant for any salon that uses a scheduling platform, accepts credit cards, or stores client data. A breach can expose names, phone numbers, appointment history, and account logins. Cyber coverage helps pay for notification, credit monitoring, and legal costs.
Product liability matters if your salon sells retail products. If a client buys a product, takes it home, uses it, and has a reaction, that is a product liability claim. General liability policies often include products-completed operations coverage, but make sure retail sales are part of the business description the carrier actually underwrote.
A commercial umbrella adds an extra layer of limits on top of your underlying policies. But not every umbrella automatically sits over every type of claim. Some may cover general liability but not professional liability unless that coverage is specifically scheduled. And an umbrella does not fix excluded claims. It is a limit extender, not a gap filler.
Talk to Your Agent About What You Actually Have
A well-insured salon typically carries a business owners policy with a professional liability endorsement, workers comp if there are employees, booth renter requirements with certificates of insurance, inland marine for tools, cyber liability for client data, and an umbrella on top. Most of it bundles together.
The key is making sure nothing falls through the gap between what you think you have and what your policy actually says. If something is missing, that is a conversation worth having with your agent before a client’s attorney has it with you.
According to the Insurance Information Institute, small businesses typically need at least property insurance, liability insurance, and workers compensation to build a solid insurance foundation.
Western Pacific Insurance is an independent agency based in Henderson, Nevada. We help salon owners and beauty business owners across Nevada, Arizona, Utah, and California build the right coverage program. Get a quote or explore our coverage across Nevada, Arizona, Utah, and California.


