
Equipment Breakdown Coverage in Utah: Protecting Your Home Systems
Utah homes work hard across the seasons. Furnaces run through cold Wasatch Front winters. Air conditioning carries the summer. When one of those systems fails on its own, many homeowners assume their policy will pay. Often it will not. Utah equipment breakdown coverage is the piece that closes that gap.
Four seasons, heavy demand
Utah weather swings hard. A furnace runs all winter in Salt Lake City and Provo. The AC takes over in summer. That year-round demand wears on motors, heat exchangers, and control boards.
Your homeowners policy is built for sudden outside events. A fire. A windstorm. The classic falling tree. It is not built for the system that fails on its own from the inside.
Where the standard policy stops
Most Utah homeowners policies exclude mechanical breakdown and certain electrical failures. So a failed furnace motor or a burned-out AC compressor often falls into a gap. No covered event caused it, so the policy steps back.
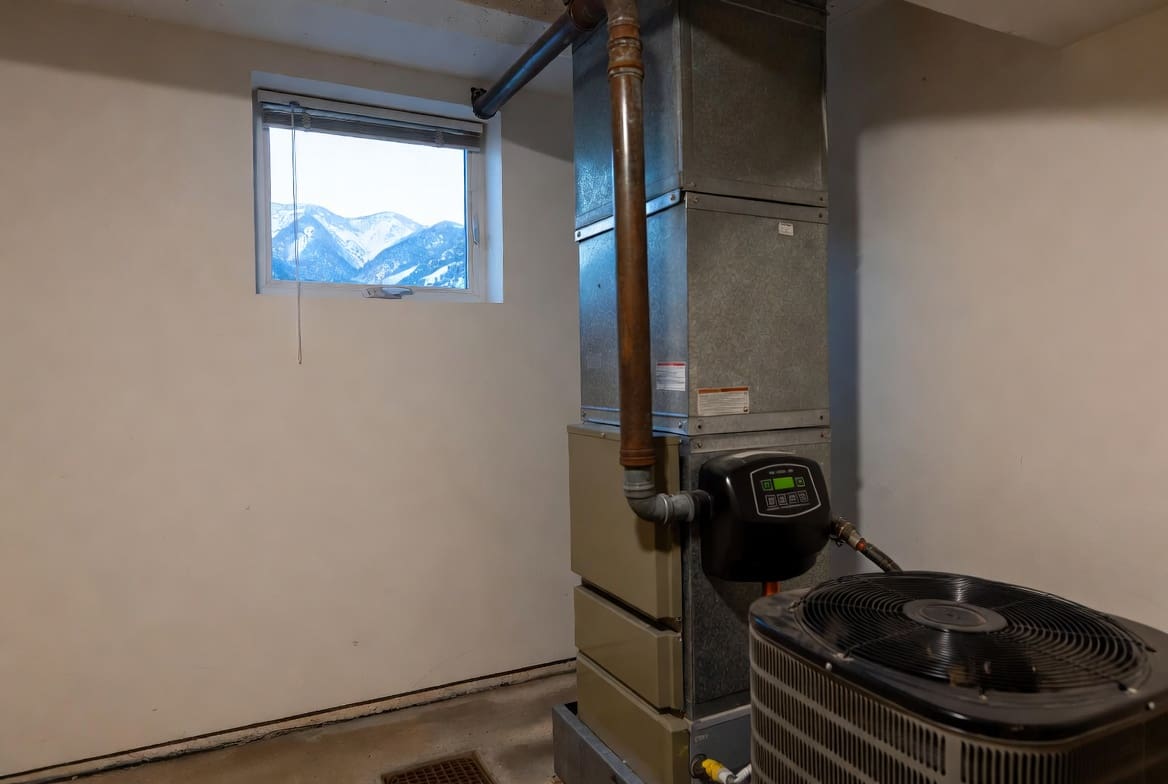
Equipment breakdown coverage steps in there. It responds to sudden, accidental failure of covered systems, including your furnace, HVAC, water heater, and major appliances.
A modern Utah home runs on machines
Count the systems in an Ogden or Lehi home. A furnace. Central air. A tankless water heater. Solar panels and an inverter. A backup generator. Each can fail without a storm involved.
Many of those repairs are expensive. Replacing several at once would be a major cost. That combined exposure is what this coverage is designed to handle.
The limits to know
It does not cover normal wear and tear. A furnace that dies of old age is usually not a sudden accidental claim. It does not cover neglect, so a system that failed from skipped maintenance can be denied.
A home warranty is a separate tool, and it is not insurance. In Utah it is a service contract that may cover wear and age. That matters because not every carrier offers equipment breakdown coverage to begin with.
Utah businesses and consequential loss
A Salt Lake restaurant depends on refrigeration and HVAC. A tech office along the Silicon Slopes corridor relies on servers and climate control. When that equipment fails, lost income and spoiled inventory can exceed the repair.
Business equipment breakdown coverage can include those losses, depending on the coverage parts selected. For a Utah business that depends on critical equipment, it is worth reviewing.
Check where you stand
Pull your declarations page and look for equipment breakdown or mechanical breakdown. Add up the systems that could fail on their own. Then ask your carrier whether the coverage is available, because plenty do not offer it.
For a clear outside reference on what this coverage typically includes, see the SmartFinancial guide to equipment breakdown coverage.
Work with a local agency
Western Pacific Insurance helps Utah homeowners and business owners sort out where this coverage fits. We can check availability across carriers or talk through whether a home warranty is the better tool.
Get a quote or learn more about our Utah coverage. For the full picture, read our complete guide to equipment breakdown coverage.


