
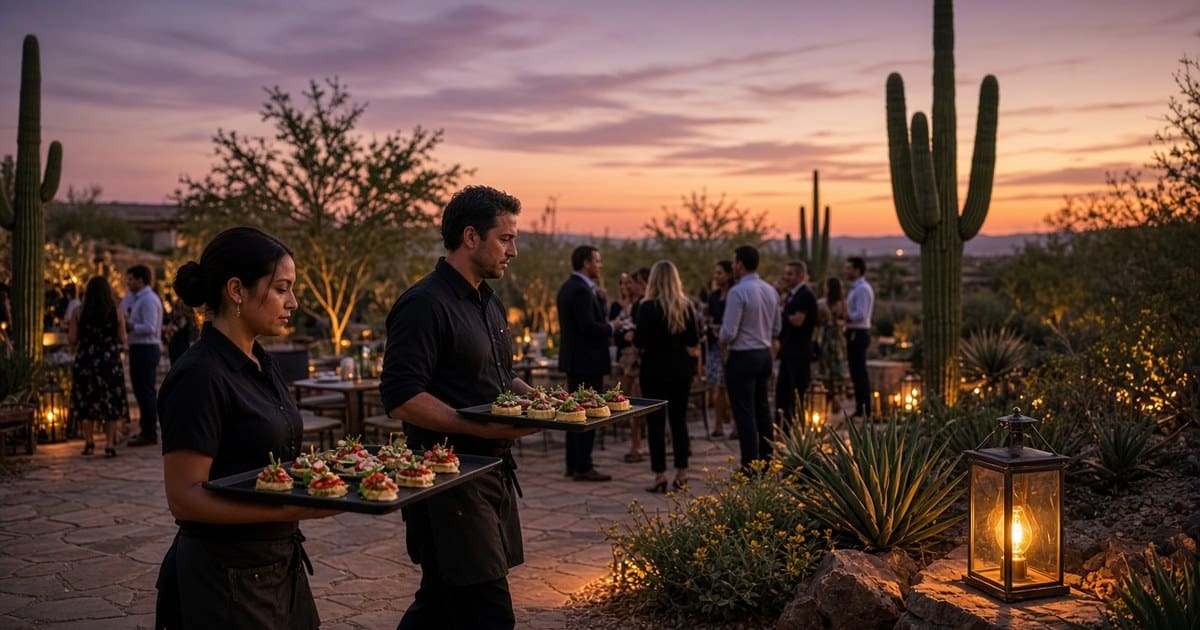
Catering in Phoenix means working outside more often than not. You might be setting up on a patio in Arcadia, a lawn at a Scottsdale resort, or a Paradise Valley estate, then driving across the Valley the next day to deliver office lunches. The busy stretch runs from fall through spring, and summer tests how well your coolers and your food safety habits hold up.
This page covers what is different about catering here. If you want each coverage explained in full first, start with our catering insurance guide. Western Pacific Insurance writes business insurance for caterers across Arizona and the rest of our four-state area.
The coverage most Phoenix caterers build around
- General liability with products and completed operations. This responds to guest injuries, venue damage, and claims that someone got sick after eating your food.
- Liquor liability. You need it when your business serves or pours alcohol. Host liquor coverage is usually not enough once you are being paid to provide drinks.
- Business auto and hired and non-owned auto. The first covers your company vans. The second covers staff who drive their own cars on your behalf.
- Workers’ compensation. This covers your kitchen and event staff.
- Inland marine and property. This protects warmers, coolers, linens, and other gear that travels, along with your kitchen and food spoilage.
Patio events, heat, and long drives
A single week can mean the 101, I-10, and Loop 202, followed by a setup where wind, dust, and direct sun are all part of the job. Heat makes temperature control the center of your food safety plan. Products coverage is what responds if a guest says they got sick. Resorts and planners commonly ask for certificates with additional insured wording, and large resort events may require higher limits or an umbrella.
Serving alcohol in Arizona
Arizona’s Department of Liquor Licenses and Control says Arizona does not have a catering liquor license. Its FAQ also states that a restaurant license (Series 12) only allows alcohol to be sold and served on the licensed premises. That means a restaurant cannot take its liquor sales to an off-site catered event under that license alone. Bar, beer and wine bar, and liquor store licenses have certain off-premises privileges.
If a client wants a bar at their event, talk with the department or a liquor attorney about the right setup before you quote it. For the insurance side, see our Arizona liquor liability page.
Workers’ compensation and food safety
The Industrial Commission of Arizona explains that employers generally need workers’ compensation from the first employee regularly employed in the business, including part-time and seasonal workers. That matters if you add people for the busy months.
Food handler training in Arizona is set locally rather than by one statewide card law. Check with Maricopa County Environmental Services and your venues to find out what they expect from your staff.
Claims Phoenix caterers plan around
Most catering claims in the Valley are ordinary. A guest trips over a generator cord on a resort lawn. A gust knocks over a tent leg or a hot beverage urn at a desert botanical venue. Food held too long in the heat leaves several guests sick after a graduation party. A staff member burns a hand on a portable burner at a summer pool event.
Each of these lands on a different part of your coverage. That is why we review general liability, auto, workers’ compensation, and equipment together instead of one at a time.
Small caterers, personal chefs, and seasonal work
Many Phoenix caterers run lean in summer and staff up from October through April. Seasonal and part-time workers still count for workers’ compensation, and a payroll audit will pick them up, so estimate payroll honestly when you buy the policy.
If you cook in clients’ homes in Paradise Valley or north Scottsdale, ask how your policy treats damage to a client’s kitchen or property in your care. Also check with your city and county about food permits for where you prepare food, since that affects what an insurer will write.
Certificates for Phoenix venues
Most venues and planners will ask for a certificate of insurance naming them as an additional insured. Send your agent the insurance section of each contract when you book. Ask whether your policy has blanket additional insured wording for written contracts, which can make repeat requests faster. For bigger events with large guest counts, a commercial umbrella can add limits on top of your primary policies.
Related pages
For vehicles, see our Arizona business auto page. If you run a truck, our Phoenix food truck insurance page is a better fit, and if you have a dining room, see Arizona restaurant insurance. We also have catering guides for Henderson, San Diego, and Lehi.
Get your Phoenix catering coverage reviewed
We do not list prices here because premiums depend on your revenue, alcohol service, staff, and claims history. To have your coverage checked against your venue contracts, gather your equipment list and your next few event contracts, then call 702-932-3105 or request a quote online.


