
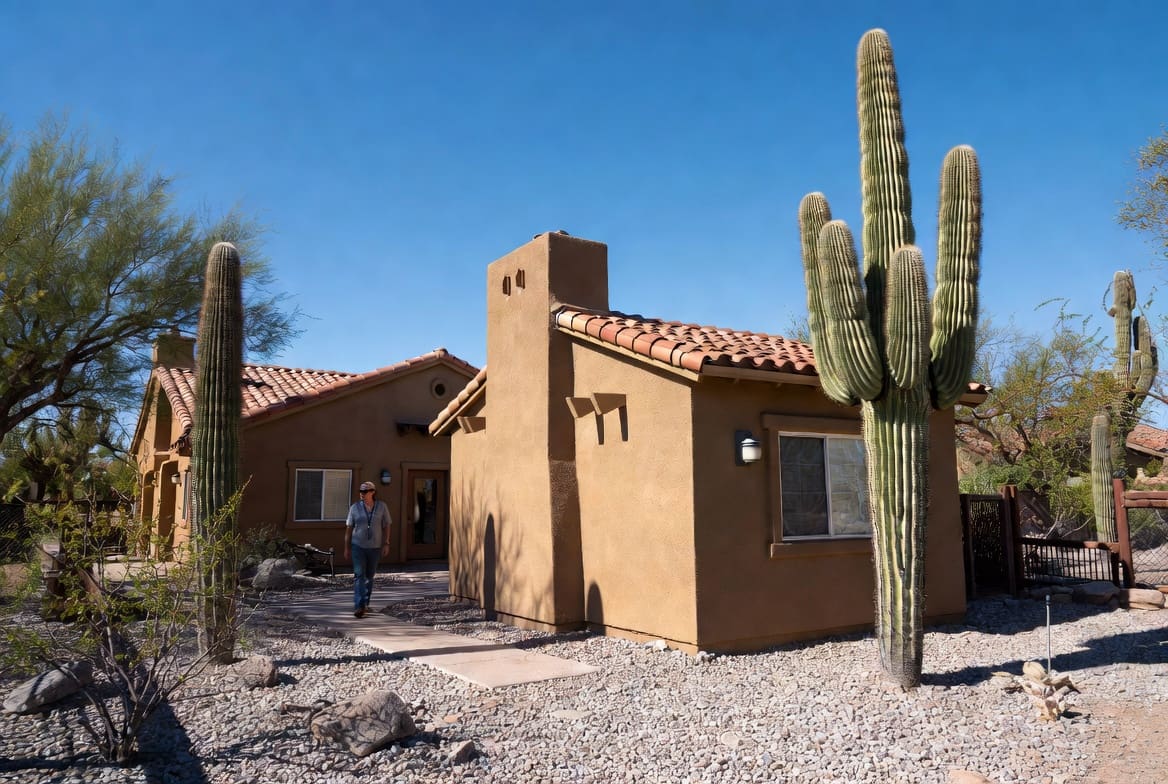
Arizona ADU Insurance: What Casita Owners Need to Check
Arizona ADU insurance rarely comes up during the build. You pull permits. The city inspects. The casita gets finished. Your homeowners policy never hears about any of it.
Arizona made casitas far easier to build. House Bill 2720 passed in 2024. It requires cities above 75,000 residents to allow accessory dwelling units on single-family lots. Phoenix, Tucson, Mesa, Scottsdale, Chandler, Tempe, Gilbert, and Glendale all fall under it.
More casitas mean more policies that no longer match the property.
Detached and attached are not the same to your policy
Your policy cares about one thing first. Is the new space attached to the house or separate from it?
A detached backyard casita is a separate building. It falls under other structures coverage. A converted attached garage was always part of the house. It stays under your dwelling coverage.
Different coverage parts. Different limits. Each one needs a separate conversation with your agent.
The other structures limit is usually a default
Other structures coverage is often set as a percentage of your dwelling limit. Ten percent is common. It varies by carrier.
Say your dwelling limit is $500,000. A ten percent default gives you $50,000 for everything detached on the lot. That includes your block wall, your shed, and your casita. Combined.
A finished casita in Phoenix or Tucson costs well beyond that. The default was sized for a shed, not a second dwelling.
The limit can usually be raised. You have to ask.
Garage conversions change your rebuild cost
An attached garage conversion stays under dwelling coverage. That part is simple.
The number underneath it is not. Your dwelling limit reflects what it costs to rebuild the house as it sits. A garage and a finished room are very different rebuilds.
The garage was a slab, framing, and a door. The conversion added insulation, finished surfaces, electrical, cooling, and often plumbing. In Arizona, the cooling load alone matters.
Same footprint on paper. Different cost to rebuild.
Renting the unit changes the question
Arizona law addressed short-term rentals directly. Under HB 2720, owner-occupancy provisions apply to short-term rental use of an ADU.
Your policy has its own view. Standard other structures coverage does not extend to structures rented or held for rental to someone who is not a tenant of the dwelling. Renting the casita may move it outside that coverage part.
Some carriers endorse the homeowners policy for one rental unit. Some want it written differently. Mercury Insurance notes that insurers may set specific conditions for ADUs used as rentals.
Ask before the tenant signs, not after.
Your tenant needs their own policy
Your homeowners policy covers your property. It does not cover a tenant’s belongings.
A renter in your casita should carry renters insurance. That protects their things and their liability.
During the build
A homeowners policy is written for a finished home. It may provide some coverage during construction, but it was not priced for a jobsite.
Check your contractor’s insurance. Confirm they are licensed. Ask for a certificate. Verify general liability and workers’ compensation if they have employees.
What to do next
Call your agent before you break ground. Ask what the finished project does to your limits. Ask whether your carrier wants the risk.
If the casita is already built, call anyway. Updating a policy is routine work.
Our complete guide to casita and garage conversion insurance walks through both project types in detail.
Western Pacific Insurance is an independent agency serving Arizona homeowners. We shop multiple carriers to find the fit for your property.
Get an Arizona quote or learn more about our Arizona coverage.


